Daily vs Weekly vs Monthly SIP: 3 Proven Math Truths for Indian Investors
Your phone buzzes at 9:00 AM. It is a notification from your investment app: “Start a ₹100 Daily SIP and build compounding magic!” It sounds incredibly persuasive. You buy your morning ₹20 chai, tap a button on Swiggy, and automatically toss a small bill into an equity mutual fund before your morning work call even starts. It feels effortless, modern, and disciplined. But when you strip away the sleek fintech marketing, does changing your investment frequency actually change your final portfolio size?
Many retail investors believe that dumping small amounts into the market every single trading day buys the market dips better than waiting for a monthly salary debit. Others worry that setting up a monthly auto-debit on the 5th misses out on mid-month market crashes. So, what is the mathematical reality of daily vs weekly vs monthly SIP mutual funds India? Does splitting your monthly investment budget into bite-sized daily chunks generate superior returns, or are you just generating clutter on your bank statement for zero extra wealth?
At InvestingLens, we do not care about financial myths or marketing hype. We care about net wealth in your bank account. In this guide, we break down the historical market data, examine cash-drag realities, and reveal the exact math behind investment frequencies in Indian mutual funds so you can set your automated wealth machine on autopilot without second-guessing yourself.
Key Takeaways
- The Return Difference Is Microscopic: Historical backtests across Nifty 50 and Nifty Midcap indices over 5, 10, and 15-year horizons show a return variance of less than 0.1% to 0.3% between daily, weekly, and monthly frequencies.
- Cash Drag Negates Daily Gains: Setting up a daily SIP means your money sits earning zero or low interest in a savings account until each daily installment drops, whereas a monthly SIP puts 100% of your dedicated capital to work instantly on payday.
- Bank Statement Nightmares: A daily SIP creates roughly 250 transaction entries in your bank passbook every year, making manual auditing and tax reporting needlessly tedious.
- Behavioral Discipline Wins: Matching your SIP frequency directly with your income stream—usually monthly for salaried employees—reduces payment bounce risks and prevents accidental overdraft fees.
- Systematic Rupee Cost Averaging Works Regardless: Rupee cost averaging is effective over months and years, not over 24-hour trading windows. Daily market noise adds stress without adding meaningful alpha.
The Myth of High-Frequency Rupee Cost Averaging
To understand why fintech apps push daily SIPs, you first have to understand the psychology behind their marketing. Brokerage apps and mutual fund platforms love daily SIPs because they lower the psychological barrier to entry. Asking you to part with ₹3,000 every month feels like a commitment. Asking you for ₹100 a day feels like giving up one cold coffee. But behavioral psychology is not the same thing as investment math.
The core theory behind rupee cost averaging is simple: when equity markets fall, your fixed rupee allocation buys more fund units. When markets rally, that same amount buys fewer units. Over time, your average purchase cost per unit drops below the average market price. Proponents of daily SIPs argue that daily frequency captures intraday volatility and micro-dips that a monthly investor misses completely.
That sounds logical on paper. But Indian equity markets do not move in neat, predictable intraday waves that reward 24-hour sampling. Over standard market cycles, equity indices trend upwards over time with intermittent spikes and corrections. When you backtest daily vs weekly vs monthly SIP mutual funds India performance over actual multi-year market cycles, that theoretical daily advantage evaporates into rounding errors.
Let us look at a practical scenario involving a typical Indian IT professional navigating this exact choice.
Real Indian Scenario: Ankit’s Nifty 50 Experiment
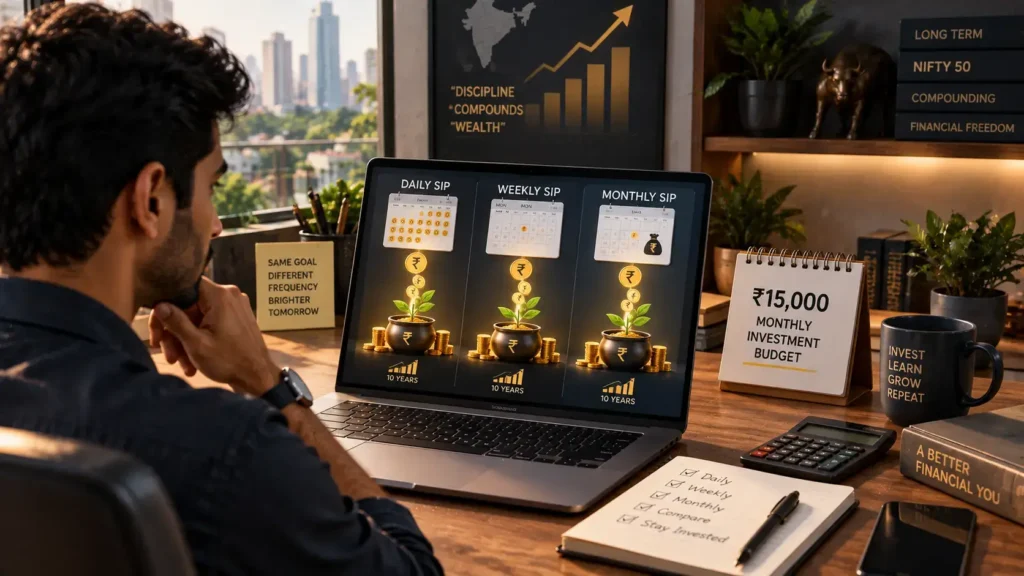
Meet Ankit, a 28-year-old software engineer based in Bengaluru. Ankit earns ₹85,000 net per month at a tech firm in Whitefield. He decides to invest ₹15,000 every month into a Nifty 50 Index Fund. Intrigued by an advertisement for high-frequency investing, Ankit debates three execution options for his ₹15,000 monthly target:
- Option A (Daily SIP): ₹700 every trading day (assuming roughly 21-22 trading days per month).
- Option B (Weekly SIP): ₹3,750 every Monday.
- Option C (Monthly SIP): ₹15,000 on the 5th of every month, right after his salary hits his HDFC Bank account.
Ankit assumes that buying equity units daily will yield a significantly higher corpus over a 10-year period because he will capture every single market drop in real time. Here is what the actual historical numbers reveal when tracking long-term index performance in India:
| SIP Frequency | Total Capital Invested (10 Yrs) | Estimated Corpus (12% XIRR) | Estimated Corpus (15% XIRR) | Net Performance Difference |
|---|---|---|---|---|
| Daily SIP | ₹18,00,000 | ₹41,20,450 | ₹49,85,200 | Baseline Comparison |
| Weekly SIP | ₹18,00,000 | ₹41,18,300 | ₹49,81,100 | -0.05% vs Daily |
| Monthly SIP | ₹18,00,000 | ₹41,12,800 | ₹49,72,400 | -0.18% vs Daily |
Look closely at those figures. Over a full decade of regular investing, the total difference between a daily SIP and a monthly SIP amounts to barely ₹7,650 on a portfolio worth over ₹41 Lakhs. That represents a negligible 0.18% variation. Why is the gap so microscopic? Because stock market cycles and compounding operate across long multi-year horizons, not single afternoons.
The Hidden Operational Costs of Daily SIPs
While the mathematical returns of daily vs weekly vs monthly SIP mutual funds India are virtually identical, the operational friction of daily SIPs is vastly higher. High-frequency investing introduces several hidden hassles that fintech apps rarely mention on their landing pages.
1. Bank Statement Overload and Audit Friction
If you run a daily SIP across three different mutual funds (for example, a large-cap index fund, a flexi-cap fund, and a mid-cap fund), your savings bank account will experience 3 auto-debits every single trading day. Over one year, that creates over 750 individual transaction entries in your bank statement.
Try scrolling through a 40-page bank statement when applying for a home loan or submitting income tax verification. Lenders and chartered accountants routinely flag cluttered statements, making it harder to track genuine transactions, UPI spends, and monthly utility payments. If you ever need to verify your monthly expenses against a standard zero-based budgeting plan, sorting through hundreds of ₹100 micro-debits becomes an absolute nightmare.
2. The Invisible “Cash Drag” Factor
To run a daily SIP smoothly, you must keep a cash cushion sitting in your primary savings account to ensure auto-debits never bounce. Money sitting in a standard savings account at an Indian bank typically earns between 2.5% and 3.5% annual interest—well below inflation.
In contrast, a monthly SIP deducted on your salary date immediately deploys 100% of your targeted investment capital directly into market assets on Day 1. By holding back cash in your savings account to feed small daily debits throughout the month, you introduce cash drag. That uninvested cash earns meager savings interest while waiting for its turn, effectively canceling out any minor statistical advantage daily rupee cost averaging might have offered.
3. Failed Debits and Penalty Charges
What happens if your savings account balance drops too low near the end of the month due to an unexpected expense? With a daily SIP, an automated payment request will still hit your bank account every single day. While many banks have stopped charging NACH/Auto-debit bounce fees for mutual fund mandates, some non-banking institutions and legacy banks still levy charges or flag repeated mandate failures. Multiple failed mandates can lead to fund houses pausing your systematic investment plan entirely.
Comparing the Options: Daily vs Weekly vs Monthly
When choosing the right frequency for your financial journey, you must evaluate how each option aligns with your income cycle, administrative patience, and long-term goals.
Daily SIP: The High-Maintenance Choice
Daily SIPs appeal to investors who enjoy active tracking and small, daily habits. If you earn a daily income—such as a freelance consultant or small business owner collecting daily UPI receipts—a daily SIP can work as an immediate cash-sweeping tool. However, for salaried employees, daily SIPs create unnecessary clutter with zero meaningful yield advantage.
Weekly SIP: The Middle Ground
Weekly SIPs pick an auto-debit day (such as every Monday or Friday). While weekly SIPs cut down bank statement entries from 250 down to roughly 52 entries per year per fund, the long-term wealth difference compared to a monthly SIP remains practically zero. It offers no structural advantage over a monthly mandate unless your cash flow arrives on a weekly basis.
Monthly SIP: The Gold Standard for Salaried Investors
For 95% of retail investors in India, the monthly SIP remains the most pragmatic, reliable, and effective wealth-building tool available. It perfectly mirrors how most households earn and allocate money. You receive your salary, pay your fixed obligations, fund your monthly SIP immediately, and spend what remains. This aligns with classic personal finance principles like the 50/30/20 Rule, automating your savings before lifestyle creep can touch your funds.
How to Match SIP Frequency to Your Cash Flow
Instead of chasing theoretical market timing through high frequencies, align your investment execution with your actual income schedule. Financial peace of mind comes from simplicity, not complexity.
If you earn a monthly salary on the last day of the month or the 1st of the month, set your monthly SIP auto-debit date for the 3rd or 5th. This gives your bank enough buffer time to clear your salary cheque while ensuring your investment money leaves your account before you spend it on impulse purchases on Swiggy or weekend outings.
Try it yourself: Open your primary bank statement from last month. Count how many individual automated debits hit your ledger. If you feel overwhelmed by lines of micro-transactions, consolidate your strategy. Move your investments to a single monthly SIP scheduled right after payday, clean up your cash flow, and track your net worth once a month instead of staring at daily Net Asset Values (NAVs).
Remember that long-term equity returns depend on market growth, time in the market, asset allocation, and underlying fund performance—not whether your transaction triggered on a Tuesday afternoon or a Thursday morning. Regulators like SEBI ensure fair NAV execution based on cut-off timings, but no regulator can compensate for an inconsistent investment habit.
FAQs
Does a daily SIP give better returns than a monthly SIP in Indian equity funds?
No, historical data shows that over 5 to 10-year horizons, the difference in XIRR returns between daily and monthly SIPs is less than 0.2%. The long-term compounding of the underlying assets far outweighs micro-differences in daily purchase prices.
Can I change my SIP frequency from daily to monthly without tax penalties?
Yes. Changing your frequency simply requires stopping your existing daily SIP mandate and registering a new monthly SIP mandate in the same mutual fund scheme. Stopping an active SIP triggers no capital gains tax because you are not redeeming existing units; you are merely changing future investment instructions.
Why do investment apps promote daily SIPs so aggressively?
Investment apps promote daily SIPs primarily for behavioral onboarding. Showing small daily numbers like ₹50 or ₹100 reduces the psychological friction of getting started for beginner investors, making them feel instantly active without requiring a large upfront commitment.
What happens if my bank balance is insufficient on my SIP auto-debit date?
If your account lacks sufficient funds, the SIP transaction fails for that cycle. While mutual fund houses do not charge penal fees for failed SIP debits, your bank might charge auto-debit bounce fees depending on your account terms. Repeated failures may cause the fund house to cancel the mandate entirely.
Final Thoughts
In personal finance, complexity is often the enemy of consistency. The debate surrounding daily vs weekly vs monthly SIP mutual funds India is largely a marketing distraction. The math clearly shows that high-frequency daily purchasing yields virtually identical returns to traditional monthly investing over real-world timelines, while adding massive administrative friction to your bank statements.
Stop overcomplicating your wealth-building system. Pick a monthly SIP date that falls 2 to 4 days after your monthly income arrives, automate the process, and let compounding do the heavy lifting over decades. Your time is far better spent advancing your career, growing your primary income, or refining your overall financial plan than tracking micro-transactions every single trading day.
Ready to streamline your portfolio? Take five minutes today to audit your active mandates, eliminate redundant micro-SIPs, and align your auto-debits directly with your payday cash flow.
This article is for educational purposes only and does not constitute financial advice. Figures, examples, and outcomes are illustrative and vary based on individual circumstances and lender policies. Always consult a certified financial advisor before making major financial decisions.
One Email a Week. Five Things Worth Knowing.
- One important financial change that actually affects you
- One practical money lesson
- One useful calculator
- One common mistake to avoid
- One guide worth reading