Non-Profit Budgeting in India: 7 Powerful Checks for Financial Control
A grant can look generous on paper and still leave an organization short of cash. A donor may release funds in instalments, a project may allow only specific expenses, and salaries still fall due every month.
That is why budgeting and financial management for non-profit organizations cannot stop at an annual spreadsheet. You need a working plan that connects each rupee to its source, permitted use, timing and evidence.
This guide walks through practical controls for Indian nonprofits: building a usable budget, protecting restricted funds, planning cash flow, monitoring variances and preparing for compliance checks. Strong budgeting and financial management for non-profit organizations also helps leaders make timely decisions when income or delivery plans change.
Key Takeaways
- Separate unrestricted funds from grants restricted to a particular purpose, project or period.
- Budget from activities and realistic costs, not from last year’s figures with a small percentage added.
- Track cash timing as well as total project income; an approved grant is not cash in the bank.
- Set approval limits, supporting-document rules and bank reconciliation routines before spending begins.
- Review actuals against budget monthly, investigate meaningful variances and record decisions.
- Check current registration, tax and foreign-contribution requirements with the relevant official sources and qualified professionals.
Build a budget around the work, not the spreadsheet
Start with activities, outputs and dates
Budgeting and financial management for non-profit organizations starts with a plain operational question: what needs to happen, where, and by when? List activities first—training sessions, field visits, counselling hours, meals served or equipment installed—then estimate the resources each activity requires.
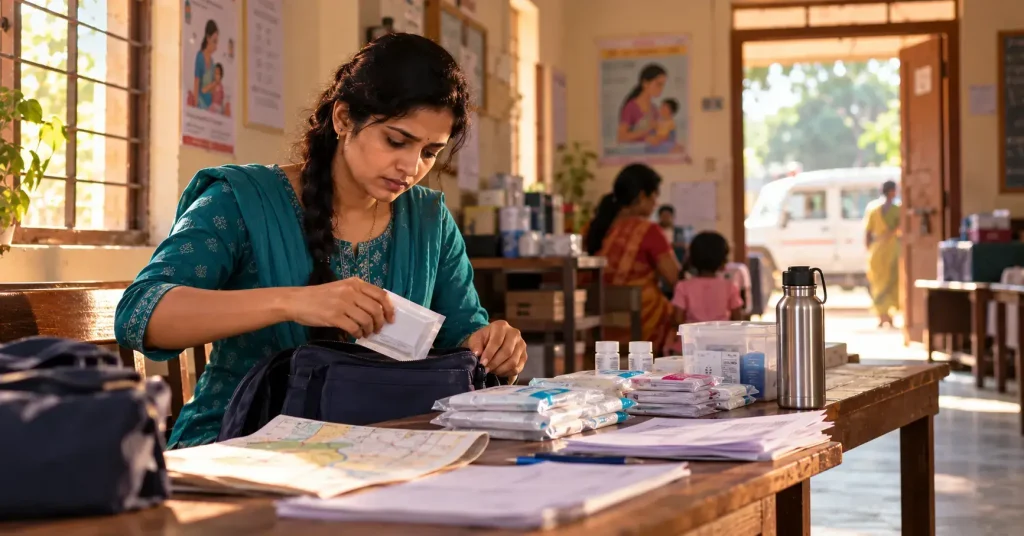
Take Budhni, a nurse coordinating a community health programme in Deoghar. Her team plans 12 outreach days across a year. If each day needs transport, basic supplies and staff time, those costs belong in the activity plan. A single line called “programme expenses” hides whether the estimate covers all 12 days or only the first few.
For budgeting and financial management for non-profit organizations, linking each cost to a planned activity makes it easier to explain estimates to staff, trustees and funders.
Use full costs, not just visible programme costs
Rent, bookkeeping, internet, safeguarding, staff supervision and audit preparation keep services functioning. Leaving them out does not make them disappear; it usually pushes the organization into unplanned fundraising or unpaid staff time.
Separate direct programme costs from shared operating costs, then use a clear allocation method for shared items. For example, a shared office cost might be allocated by staff time or programme use. Document the method and apply it consistently. Don’t quietly charge the same expense to two grants.
Show assumptions beside the numbers
A budget should explain how its estimates were formed. Record quantities, unit costs, timing and assumptions—such as the number of participants, travel distance or expected vendor price. Keep quotations or recent invoices where they support material estimates.
For a 20-person workshop, a line for refreshments is easier to review when it shows 20 participants multiplied by an estimated per-person cost, rather than a round lump sum. Prices move. A transparent assumption makes the change visible instead of turning it into a surprise.
Budgeting and financial management for non-profit organizations: protect restricted grants and plan cash flow
Keep a source-and-use map for every grant
In budgeting and financial management for non-profit organizations, the same bank balance can contain money with different rules. One donor may fund training materials; another may cover a defined period of staff costs. Your records need to preserve those distinctions, whether through accounting codes, project ledgers or another reliable system.
Shrikant, a programme manager in Mapusa, receives a grant for coastal awareness sessions. The grant budget allows field travel and learning materials, but not a general office renovation. If the organization pays a shared bill from the grant, the allocation must follow the agreement and be supported by records. “There was money in the account” is not proof that a charge was permitted.
Forecast when money arrives and when bills fall due
Annual totals can conceal a cash crunch. If a donor’s second instalment is due in September but salaries and rent are payable in July, the organization needs a short-term cash plan. Show expected receipts by month, committed expenses, payroll dates and the minimum cash needed to keep essential operations going.
Don’t treat a proposal submitted, a verbal assurance or an approved but unreleased instalment as available cash. Label each receipt by status: received, contractually scheduled, pending or uncertain. That small discipline helps trustees distinguish a temporary timing gap from a genuine funding shortfall.
As part of budgeting and financial management for non-profit organizations, update the cash forecast whenever a grant payment date or major expense changes.
Read the grant agreement before committing
Check the permitted cost categories, project dates, reporting deadlines, procurement conditions, treatment of interest and rules for unspent balances. The exact terms vary. A budget approved by a donor does not override the signed agreement.
For foreign contributions, verify current requirements through the Ministry of Home Affairs and the applicable FCRA rules before receiving or using funds. For domestic CSR support, check the relevant MCA requirements and agreements. Requirements can change; don’t rely on an old checklist copied from another organization.
Set controls people can actually follow
Write down who can approve what
A control system is only useful if staff can use it on a busy Tuesday. Define spending limits, who approves each level, what documents are required and how exceptions are recorded. Separate the person requesting a purchase from the person approving and paying it wherever staffing allows.
Jamna, an operations lead at a small education nonprofit in Ahmedabad, may be able to approve routine local purchases up to a set limit, while larger purchases need a second approver. The specific limit should reflect the organization’s scale and risk; the key is that it is written, authorized and applied consistently.
Clear, workable controls are a practical part of budgeting and financial management for non-profit organizations, not a separate administrative burden.
Use simple procurement and payment checks
For higher-value purchases, establish a proportionate quotation process and keep the comparison or reason for selecting a supplier. Confirm that the goods or services were received before payment. For recurring vendors, review invoices against the contract or agreed rates.
These checks are not about treating every vendor as suspicious. They protect staff too. If a trustee later asks why one supplier was chosen, a dated record of prices, quality and delivery terms is far stronger than someone’s memory.
Reconcile accounts and restrict access
Reconcile each bank account to the accounting records at least monthly. A reviewer who did not prepare the reconciliation should check it where the team size permits. Investigate old unreconciled items promptly: a cheque recorded but never cleared, a duplicate bank debit or an unexplained transfer can distort the available balance.
Limit access to online banking and accounting tools according to job needs. Use individual logins and maintain a record of changes to payment details. Shared passwords make it harder to establish who authorized a transaction, even when everyone is acting in good faith.
Monitor actual spending without hiding the story
Compare actuals with budget every month
Budgeting and financial management for non-profit organizations requires a regular review, not an annual post-mortem. Compare budget, actual spending and the latest forecast for each project and for the organization as a whole. Include commitments such as signed contracts, not only payments already made.
Try it yourself: select one project and compare its budget with actuals for the last month and year to date. Add a short explanation beside each material difference. A positive variance can mean savings, but it can also mean planned work has not happened yet.
When budgeting and financial management for non-profit organizations includes routine variance reviews, teams can act on emerging delivery problems before they become year-end surprises.
Make variance reporting useful
Suppose a programme has used only 40% of its travel budget halfway through the year. That might reflect lower fares—or cancelled field visits. The first is a cost saving; the second may signal delayed delivery. The number alone cannot tell you which.
Agree on a review threshold that suits the organization, such as investigating a variance above a set rupee amount or percentage. Record the cause, likely effect, owner and next action. If a donor’s approval is required to move funds between categories, obtain it before reallocation rather than explaining the change after the fact.
Give the board a short, decision-ready view
Board members need more than a dense ledger export. A useful monthly or quarterly pack shows cash available, restricted balances, income received versus expected, major budget variances, outstanding commitments and any compliance deadlines or control issues.
Keep the presentation direct. If a programme is likely to run short, say how much, when the gap appears and what decisions are available—such as rescheduling an activity or seeking donor approval. Don’t make a forecast look healthy by counting uncertain income as confirmed.
Prepare for year-end and compliance checks
Keep records close to the transaction
Store approvals, invoices, receipts, contracts, attendance records and payment evidence in an organized system. Use consistent file names that identify the project, date and transaction. A document collected months later is easier to misplace and harder to verify.
Set a retention policy based on applicable law, donor contracts and professional advice. Make sure a second authorized person can locate essential records if the primary finance staff member is away. Small organizations are particularly exposed when knowledge sits in one person’s inbox.
Check tax and registration requirements each year
Tax exemptions and donor-deduction rules depend on the organization’s registration, approvals, filings and current law. Do not assume an old certificate or a previous year’s treatment is automatically sufficient. Check current Income Tax Department guidance and consult a qualified chartered accountant for organization-specific questions.
Likewise, foreign contribution and CSR obligations depend on the organization’s circumstances and the relevant rules. Keep a calendar of renewal, filing and reporting dates, assign an owner to each deadline, and retain proof of submission. A calendar entry without an accountable person is just decoration.
Sound budgeting and financial management for non-profit organizations includes confirming that financial records, reporting deadlines and regulatory obligations remain aligned throughout the year.
FAQs
How often should a nonprofit review its budget?
Many organizations review actuals and cash flow monthly, then update the forecast when funding, costs or delivery dates change. Board reporting can follow the organization’s governance calendar and donor commitments.
How should a nonprofit handle restricted grant money?
Track each restricted grant separately in the accounts or project ledger, follow its agreement and retain evidence for every charge. Don’t transfer costs between grant categories without checking the donor’s rules and obtaining approval where required.
Can a nonprofit spend grant money on administration?
That depends on the grant agreement, applicable rules and the cost’s purpose and allocation. Read the terms before committing funds, and document shared-cost methods clearly.
What should a nonprofit budget report show?
Show the approved budget, actuals, forecast, restricted balances, cash timing, material variances and commitments. Add concise explanations so decision-makers can see whether a difference reflects savings, delay or a delivery risk.
Final Thoughts
A nonprofit’s financial discipline is not separate from its mission. It is what lets staff explain where funds went, spot cash pressure early and keep promises to communities and donors without confusing restricted money with money freely available for any purpose.
Start with one current project budget: check its assumptions, grant conditions, cash dates and approval trail. For broader templates and money-management context, visit the Budgeting and Money Management hub and the article “Budgeting and Money Management Skills: 5 Proven Steps to Master Your Cash Flow.” For legal, tax or accounting decisions, verify current official requirements and speak with a qualified professional.
The examples above are simplified, and their figures are assumptions used to show how the numbers work.
This article is for educational purposes only and does not constitute financial advice. Figures, examples, and outcomes are illustrative and vary based on individual circumstances and lender policies. Always consult a certified financial advisor before making major financial decisions.
One Email a Week. Five Things Worth Knowing.
- One important financial change that actually affects you
- One practical money lesson
- One useful calculator
- One common mistake to avoid
- One guide worth reading