Education Loan vs Savings India: 5 Proven Truths for Funding College
You have spent years watching your child study late into the night, dreaming of an engineering degree from a top IIT, a medical seat, or perhaps an MBA abroad. As an Indian parent, your immediate, biological instinct is to do whatever it takes to fund that dream. You might be thinking about breaking your Fixed Deposits, liquidating your mutual funds, or even pulling money from your Employee Provident Fund. You tell yourself, “I will work a few extra years; my child’s future comes first.”
It is a noble thought. But in the cold, hard light of financial reality, it can be a devastating mistake.
Higher education costs in India are growing at an alarming rate of 10% to 12% annually, far outpacing general inflation. A premier private engineering course that costs ₹15 Lakh today could easily touch ₹35 Lakh by the time your middle-schooler is ready for college. When faced with these massive numbers, the ultimate dilemma arises: should you empty your hard-earned nest egg, or make your child take a student loan? This guide to the debate of education loan vs savings India will break down the math, the psychological traps, and the exact strategies you need to protect your retirement while securing your child’s career.
Key Takeaways
- Retirement cannot be financed: You can get a loan for education, but no bank in India will give you a loan to fund your retirement.
- Tax benefits favor loans: Section 80E of the Income Tax Act allows unlimited deductions on education loan interest payments for up to 8 years.
- Skin in the game: An education loan builds financial discipline and responsibility in young graduates from day one.
- The hybrid approach is king: The most secure path is a calculated mix of 70% savings and 30% low-cost education loans.
- Avoid emotional liquidations: Breaking long-term compounding assets like equity mutual funds early destroys your lifetime wealth generation.
The Brutal Math of the Education Loan vs Savings India Dilemma
Let us look at a real-world scenario to understand the stakes. Meet Ramesh, a 48-year-old software project manager in Bengaluru who earns ₹1.8 Lakh per month. His daughter, Ananya, has secured admission to a prestigious private business school. The total cost for the two-year program, including hostel fees and laptop expenses, is ₹24 Lakh.
Ramesh has ₹25 Lakh sitting in a mix of long-term equity mutual funds and public provident fund (PPF) accounts. This money was originally earmarked for his retirement corpus. Ramesh is torn. Should he liquidate these assets to pay the fees outright, or should he apply for an education loan?
The Cost of Liquidating Your Savings
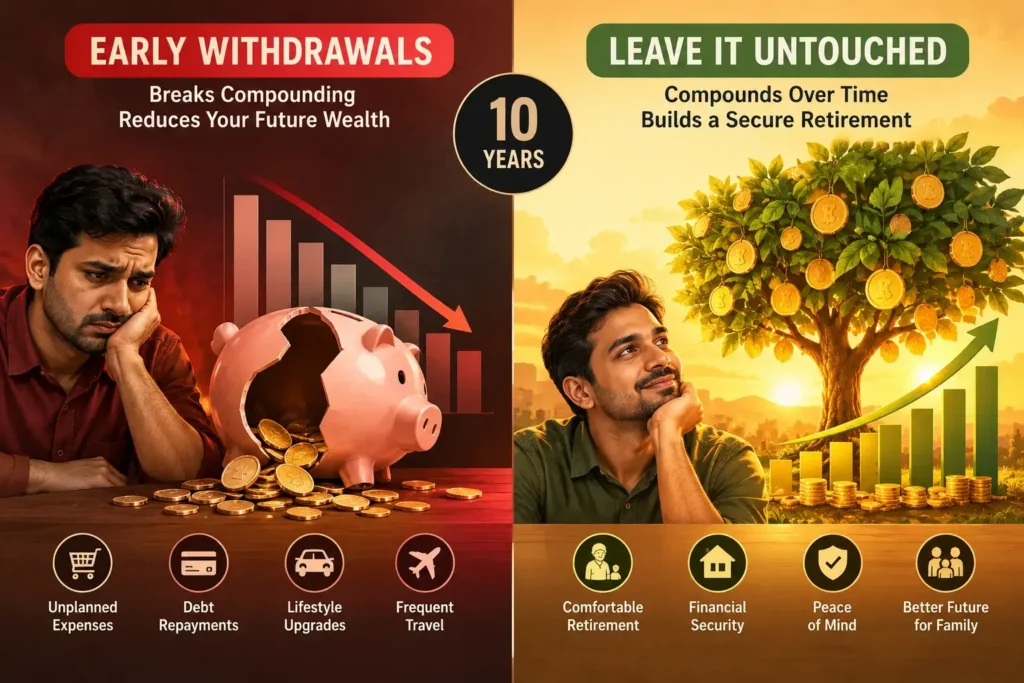
If Ramesh decides to use his savings, he pays exactly ₹24 Lakh today. He leaves the bank with zero debt. It sounds clean, right? It isn’t.
By pulling ₹24 Lakh out of his compounding retirement pool, Ramesh loses the future growth of that money. If that ₹24 Lakh had remained invested in equity mutual funds earning a conservative average return of 12% per year, it would have grown to approximately ₹74.5 Lakh in 10 years, just as Ramesh reaches his retirement age of 58. By spending his savings now, Ramesh is not just spending ₹24 Lakh; he is sacrificing ₹74.5 Lakh of his retirement security.
The True Cost of an Education Loan
Now, let us look at the alternative under the education loan vs savings India lens. Ramesh decides to take an education loan of ₹24 Lakh at an interest rate of 9.5% per annum with a repayment tenure of 7 years, starting after Ananya’s 2-year course finishes.
Here is how the loan repayment numbers actually look for Ramesh and Ananya:
| Loan Component | Details and Figures |
|---|---|
| Principal Loan Amount | ₹24,000,000 |
| Interest Rate (Floating) | 9.5% per annum |
| Moratorium Period (No EMIs) | 2 Years (During Course) |
| Repayment Tenure | 7 Years (84 Months) |
| Estimated Monthly EMI | ₹39,150 |
| Total Interest Payable | ₹8,88,600 |
| Total Repayment Amount | ₹32,88,600 |
At first glance, paying ₹32.88 Lakh back to the bank looks much worse than spending ₹24 Lakh of your own money. But this ignores the power of compounding. Because Ramesh left his ₹24 Lakh retirement savings untouched, that money grew to ₹74.5 Lakh over the same decade. Even after subtracting the total loan repayment of ₹32.88 Lakh, Ramesh is still net-positive by more than ₹41 Lakh. This is the counter-intuitive reality of leverage in personal finance.
The Hidden Advantages of Choosing a Student Loan
In India, debt is often viewed as a cultural taboo, a sign of financial failure. Parents feel a sense of guilt if they cannot pay for their child’s education out of pocket. But when evaluating education loan vs savings India, you must separate emotion from math. Loans carry specific, structural advantages that savings simply cannot match.
Tax Relief Under Section 80E
The Income Tax Department offers a major incentive for choosing a loan. Under Section 80E of the Income Tax Act, the entire interest component paid on an education loan is fully deductible from your taxable income. There is no upper limit on this deduction.
If you fall in the highest tax bracket of 30%, a 9.5% interest rate effectively feels like roughly 6.65% after tax savings. This deduction is available for a maximum of 8 years or until the interest is fully paid off, whichever comes first. This benefit is only available if you take the loan from a scheduled Indian bank or an approved financial institution, not from private local lenders.
Building the Child’s CIBIL Score and Financial Responsibility
When your child is the primary borrower and you act as the co-applicant, the loan becomes their responsibility once they secure a job. Making regular EMI payments on time is the single fastest way for a young graduate to build an excellent credit history.
A strong CIBIL score early in life will help them secure better rates on home loans or car loans down the line. Moreover, knowing that a portion of their first salary will go toward paying off their education instills a deep sense of financial discipline. It prevents the early-career lifestyle inflation that traps so many young professionals in India today.
Preserving Your Liquidity for Emergencies
Life does not stop when college begins. If you empty your liquid savings to pay college fees, what happens if there is a medical emergency in the family? What if you face a sudden job loss or a salary cut?
Without an emergency fund, you might be forced to take high-interest personal loans or credit card debt to survive. Keeping your savings intact ensures you maintain a robust cash cushion. If you are unsure how much cash you need to keep aside, check out our Emergency Fund Calculator India to map out your safety net before committing funds to college fees.
How to Create a Balanced, Hybrid Funding Strategy
You do not have to choose one extreme. The smartest Indian households use a hybrid strategy that combines both savings and loans to minimize interest costs while protecting parental retirement.
Step 1: The 70-30 Rule of College Funding
Aim to fund up to 70% of the total college expenses using dedicated, low-risk savings that you have built up over the years. This can include your PPF, tax-free FDs, or specific mutual funds. Take an education loan for the remaining 30%. This keeps the monthly EMI burden highly manageable for your child after graduation while ensuring you do not touch your core retirement accounts.
Step 2: Start an Early SIP Dedicated to Education
If your child is still young, time is your greatest ally. Instead of waiting until they turn 18, start a dedicated monthly Systematic Investment Plan (SIP) in diversified equity mutual funds today. Even a small, regular investment can grow into a massive corpus over 10 to 15 years, reducing your reliance on loans later on. For a practical guide on how to structure your monthly investments, read our breakdown of how to budget on a Rs. 30,000 monthly salary in India to find hidden savings in your monthly cash flow.
Step 3: Shop Around for the Best Loan Terms
Do not just accept the first loan offer from the bank where you hold a savings account. Compare rates across public sector banks like SBI, private lenders, and specialized non-banking financial companies (NBFCs). Public sector banks often offer lower interest rates and special discounts of 0.5% for female students, though their processing times can be longer.
FAQs
Is interest on an education loan tax deductible for parents?
Yes, if you are the co-signer or legal guardian of the student and you are the one paying the EMIs, you can claim the full interest deduction under Section 80E of the Income Tax Act.
Should I break my PPF or EPF to pay for my child’s college?
No. Breaking your long-term, tax-free retirement accounts like PPF or EPF ruins your compounding benefits and leaves you vulnerable in your senior years. Use an education loan instead.
What is the moratorium period in an Indian education loan?
It is a holiday period granted by banks, typically lasting for the duration of the course plus 6 to 12 months after graduation, during which the student is not required to pay EMIs.
Final Thoughts
The emotional urge to clear your bank accounts for your child’s education is understandable, but it is rarely the smartest financial move. When you look at the comparison of education loan vs savings India, the math consistently favors preserving your compounding retirement assets and using structured, tax-efficient student loans to bridge the gap. Your child has an entire career ahead of them to pay off a low-cost loan; you do not have the time to rebuild a lost retirement fund.
Take a seat with your child. Have an open, honest conversation about the costs of higher education. By involving them in the process and choosing a balanced, hybrid funding plan, you are not just funding their degree—you are teaching them their very first, invaluable lesson in real-world personal finance.
This article is for educational purposes only and does not constitute financial advice. Figures, examples, and outcomes are illustrative and vary based on individual circumstances and lender policies. Always consult a certified financial advisor before making major financial decisions.
One Email a Week. Five Things Worth Knowing.
- One important financial change that actually affects you
- One practical money lesson
- One useful calculator
- One common mistake to avoid
- One guide worth reading