Teaching Teens to Budget: 7 Proven Pocket Money Habits to Start Today
Your teenager can calculate the price of a gaming subscription faster than the cost of ordering Swiggy twice a week. That is not a character flaw. It is a sign that money decisions are happening before anyone has shown them how to plan.
Pocket money gives your teen a small, real budget to practise with. The goal is not to control every ₹50. It is to help them understand what money needs to cover, what can wait and how a small choice today affects next week.
This guide gives you practical ways to teach budgeting and money management for teens at home, using everyday Indian expenses and conversations that do not turn into a monthly argument.
Key Takeaways
- Agree on a clear pocket-money amount and what it is meant to cover.
- Use a simple written or phone-based tracker, not a complicated spreadsheet.
- Help your teen divide money into spending, saving and shared costs.
- Let small mistakes teach a lesson without rushing to refill the wallet.
- Discuss digital payments, subscriptions and online safety alongside spending.
- Review the plan together each month and adjust it as your teen’s needs change.
Start with a clear pocket-money agreement
Decide what the money needs to cover
“Here is your pocket money” sounds simple, but it leaves the most important question unanswered: what is it for? Is it only for snacks and outings, or does it also cover mobile data, stationery and occasional transport? If parents and teens have different answers, the first overspend is almost guaranteed to become a dispute.
Take Dhruv, a 16-year-old student in Vadodara. His parents agree to give him ₹1,200 a month for school-day snacks, an occasional outing and small personal purchases. Bus fare and required school supplies remain separate family expenses. That boundary matters. Dhruv can make choices without being expected to pay for essentials he never agreed to manage.
Make the amount predictable
A fixed monthly amount is easier to plan around than unpredictable cash handed over whenever someone asks. A weekly amount can suit a younger teen who is still learning to pace spending; a monthly amount gives an older teen more practice with longer-term planning. Neither schedule is automatically right for every family.
Write down the amount, payment date and categories it covers. Keep the arrangement realistic for your household. Budgeting and money management for teens is not about copying what another family gives; it is about making the rules visible and consistent. This clear starting point makes budgeting and money management for teens a practical routine rather than an abstract lesson.
Separate needs from extras without shaming
A need is something the agreed plan must cover; an extra is a choice that can be delayed or skipped. The distinction depends on the agreement. A notebook required for class may be a need. A second bubble tea after school is probably an extra. Talk about the choice, not whether your teen is “good” or “bad” with money.
Teach a simple plan before the money is spent
Give every rupee a job
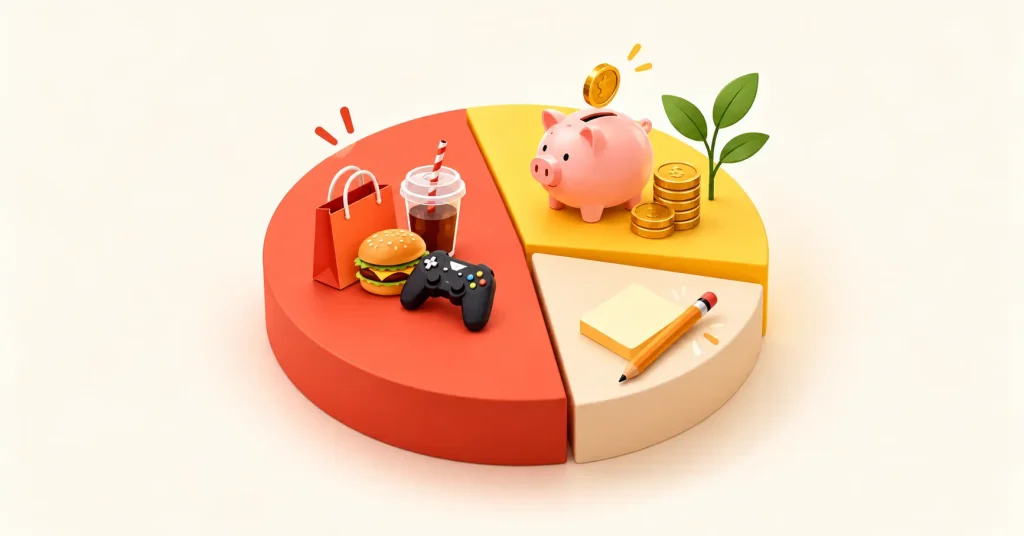
Budgeting means deciding in advance how available money will be used. It does not mean banning fun. A beginner-friendly plan can split pocket money among spending now, saving for a goal and a small buffer for an unexpected cost. A buffer is money left unassigned so one forgotten expense does not wreck the whole plan.
Ligia, a 15-year-old student in Margao, receives ₹1,000 a month. Her family helps her set aside ₹600 for snacks and outings, ₹300 toward headphones she wants, and ₹100 as a buffer. If she spends ₹180 on a café visit, she can see what remains for the rest of the month. The numbers are a practice example, not a template every family needs to use. Examples like this show how budgeting and money management for teens can fit around a real goal and a realistic amount.
Use a goal teens actually care about
“Save for the future” is too vague to motivate most teenagers. A specific goal gives saving a finish line: a book, a sports item or a contribution toward a planned outing. If something costs ₹2,400 and the teen puts aside ₹300 each month, the simple target takes eight months, before considering any change in price.
Try it yourself: ask your teen to name one purchase they want, find its current price and work out how many weeks or months of saving it would take. The point is not to promise that the item will stay at that price. It is to practise turning a want into a plan.
Make tracking almost effortless
A notes app, a paper page or a basic spreadsheet can record three things: date, amount and reason. For example: “Saturday, ₹120, snacks with friends.” A teenager does not need a finance app to learn the habit. If cash disappears into a drawer or UPI payments blur together, a quick daily note can show where the money went.
Review the record once a week for five minutes. Ask, “Was that worth it?” or “What do you want to leave more money for next week?” Those questions invite reflection. A surprise audit of every chai purchase usually invites defensiveness.
Make digital spending part of the lesson
Explain why UPI can feel like free money
Digital payments remove the visible moment of handing over cash. A ₹20 chai or a ₹150 snack still costs money, but tapping a phone can make each purchase feel smaller than it is. Show your teen how to check the payment history and compare it with their plan. Do not treat a payment app balance as a spending limit.
Bimla, a 17-year-old in Kullu, uses UPI for small purchases during the week. Her family’s monthly check-in reveals that several low-cost snacks added up to ₹500. Nothing was outrageous on its own. Seeing the total helped her decide to keep some cash aside for a weekend activity instead.
Look for subscriptions and repeat charges
Streaming, games and app memberships can renew automatically. A subscription is a recurring payment that continues at set intervals until it is cancelled. Teach your teen to check the amount, renewal date and cancellation process before signing up, including whether a free trial becomes paid. If a parent’s card is being used, agree in advance who is responsible for checking the renewal.
Practise basic payment safety
Budgeting and money management for teens also includes protecting access to money. The RBI advises users not to share their UPI PIN, which authorises a payment and should never be shared. A request to scan a QR code to “collect” a prize or refund deserves scrutiny. Discuss what your family expects if a payment goes to the wrong person or a suspicious message arrives.
Keep the conversation calm and practical. Teens are more likely to report a mistake quickly if they expect help rather than an immediate lecture. For family-wide spending routines, the Budgeting and Money Management hub can help connect these small habits to a broader household plan.
Let small mistakes happen, then review them
Do not refill the budget automatically
If your teen spends the whole month’s outing money in the first week, the discomfort is part of the lesson. That does not mean letting a young person go without food, transport or another agreed essential. It means separating essentials from discretionary spending and not quietly topping up the fun-money category every time it runs out.
When the money is gone, talk through what happened: Was the plan unclear? Did an unexpected cost come up? Was a group outing more expensive than expected? Budgeting and money management for teens improves through honest review, not punishment or rescue without discussion.
Adjust the plan when the facts change
School timetables, travel needs and social plans change. A budget that worked during exams may not fit a month with a class event. Review the amount and categories together rather than pretending last month’s plan still applies. If the family cannot increase pocket money, explain the constraint plainly and look at what can be reprioritised.
Use a monthly check-in, not a courtroom
Set a short, regular check-in. Ask what worked, what surprised your teen and what they want to do differently next month. Keep the conversation about decisions and trade-offs, not character. A teenager who admits they spent too much on a game has offered you a useful opening; turning that admission into a speech can close it.
FAQs
How much pocket money should I give my teenager?
There is no universal amount; it depends on your household budget, your teen’s age and what the money is expected to cover. Agree on the categories first, then choose an amount the family can provide consistently.
What is the best way to teach a teenager to budget?
Start with a predictable amount, a few clear spending categories and a simple record of purchases. Review the plan together regularly so your teen can learn from real choices without being shamed for small mistakes.
Should parents give teenagers pocket money every week or every month?
Weekly payments can make it easier for younger teens to practise pacing; monthly payments provide more experience planning over a longer period. The useful schedule is the one your family can keep consistent and your teen can manage.
Should I give my teenager more pocket money if they run out?
First check whether the spending money ran out or an essential expense was missed. A discretionary shortfall can be a learning moment, while agreed essentials need a separate, clear plan.
Final Thoughts
Your teen will make imperfect money choices. So do adults. The useful difference is that a small pocket-money decision can provide practice before rent, loan repayments or a full monthly salary are involved.
Start with one conversation: decide what pocket money covers, choose a simple way to track it and set a date for a short review. Then let your teenager do some of the thinking. That is where budgeting and money management for teens becomes a skill they can carry beyond the school years.
Related reading: The Real Cost of Your Daily Chai and Swiggy Habit shows how small daily spends add up, and Zero-Based Budgeting for Indian Households explains the give-every-rupee-a-job idea in more detail.
The examples above are simplified, and their figures are assumptions used to show how the numbers work.
This article is for educational purposes only and does not constitute financial advice. Figures, examples, and outcomes are illustrative and vary based on individual circumstances and lender policies. Always consult a certified financial advisor before making major financial decisions.
One Email a Week. Five Things Worth Knowing.
- One important financial change that actually affects you
- One practical money lesson
- One useful calculator
- One common mistake to avoid
- One guide worth reading