Die With Zero, Decoded: Key Ideas and What Fits India
Disclosure: some links on this page are affiliate links. If you buy through them, Investing Lens may earn a small commission at no extra cost to you. This never changes what we recommend. Content is educational, not investment advice. As an Amazon Associate I earn from qualifying purchases.
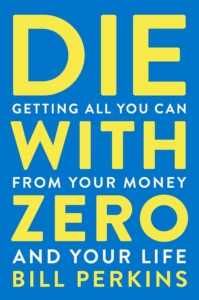
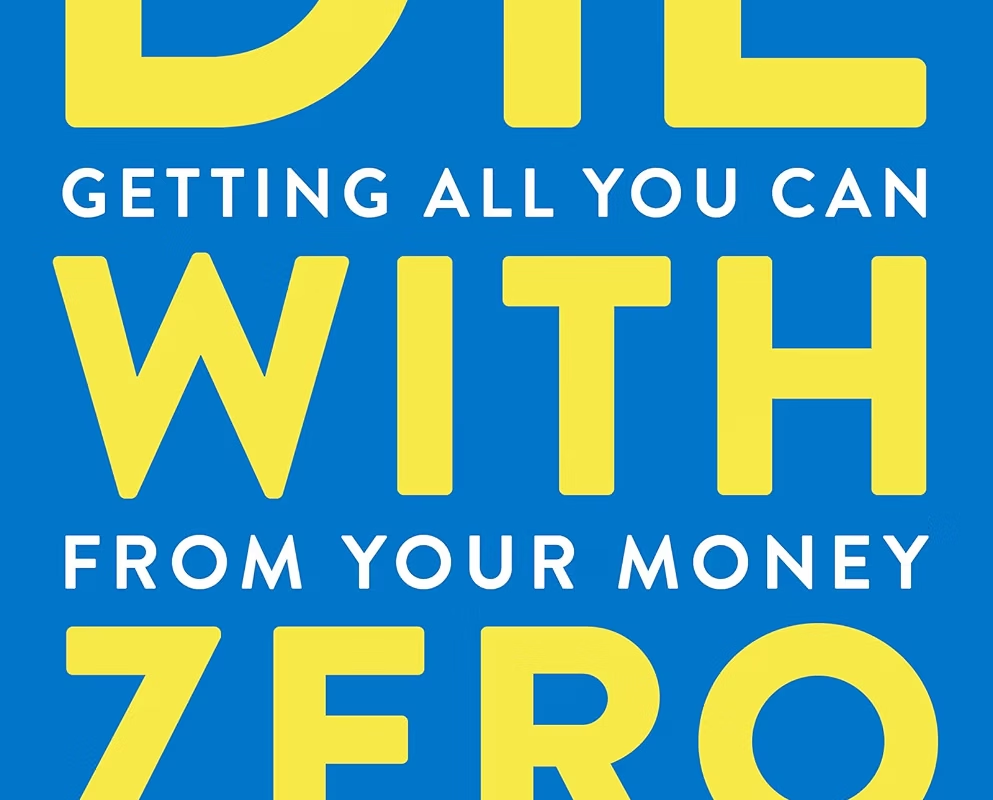
Die With Zero
In short, Bill Perkins wants to rescue you from over-saving and under-living.Regardless of your age, Die with Zero will teach you Perkins’s plan for optimizing your life, stage by stage, so you’re fully engaged and enjoying what you’ve worked and saved for.
The book “Die With Zero” by Bill Perkins advocates for prioritizing experiences over saving money for retirement. It encourages readers to focus on making memorable moments throughout their lives rather than just accumulating wealth.
The one-line idea
The core message of the book is to maximize memorable experiences in life instead of merely saving for the future.
The key ideas
Maximizing Memorable Experiences
The philosophy presented in the book encourages individuals to seek out and prioritize experiences that create lasting memories. This approach suggests that life is about more than just financial accumulation; it’s about the richness of experiences.
Do this: Make a list of experiences you want to have and start planning them now.
Experience Bucketing
Perkins introduces the concept of ‘experience bucketing’ to help readers plan and organize meaningful life experiences. This method allows individuals to categorize and prioritize experiences throughout different stages of their lives.
Do this: Create buckets for different types of experiences you want to pursue over the years.
Understanding Your Net Worth Curve
The book discusses the importance of understanding one’s ‘net worth curve’ to effectively convert earnings into memories. By recognizing how wealth can be transformed into experiences, readers can make more informed decisions about spending.
Do this: Assess your current financial situation and identify how much you can allocate for experiences.
Evaluating Experiences
Readers learn to evaluate whether to invest in experiences based on their ‘spend curve’ and ‘personal interest rate.’ This evaluation helps in determining the best times to spend on experiences for maximum enjoyment and impact.
Do this: Reflect on your spending habits and consider how they align with your personal interests.
Personal Anecdotes
Perkins uses personal stories and anecdotes from others to illustrate his points about the relationship between time, money, and happiness. These narratives serve to reinforce the book’s message and make it relatable.
Do this: Share your own experiences with friends and family to inspire discussions about the value of experiences.
A Contrarian View on Financial Planning
The book presents a contrarian view on financial planning, suggesting that living fully is more important than saving excessively. This perspective challenges conventional wisdom about retirement savings and spending.
Do this: Rethink your financial goals to include experiences that bring joy rather than just focusing on savings.
What readers say
Readers appreciate the fresh perspective on financial planning and the emphasis on experiences. Many find the ideas thought-provoking and feel encouraged to prioritize happiness over mere financial security.
Where this doesn’t fit India
In the Indian context, the idea of prioritizing experiences over savings may face challenges. Factors such as high healthcare costs, family obligations, limited pension schemes, tax implications, and inflation of the Indian Rupee can make it difficult for individuals to embrace this philosophy fully.
Who should read it, and who should skip it
This book is suitable for individuals seeking a new perspective on financial planning and those who want to focus on enriching their life experiences. However, those who prefer traditional financial advice or have significant financial responsibilities may find it less applicable.
Sources we used
This article is for education only and is not investment, tax or financial advice. Consider speaking to a SEBI-registered investment adviser for personal decisions.
This article is for educational purposes only and does not constitute financial advice. Figures, examples, and outcomes are illustrative and vary based on individual circumstances and lender policies. Always consult a certified financial advisor before making major financial decisions.
One Email a Week. Five Things Worth Knowing.
- One important financial change that actually affects you
- One practical money lesson
- One useful calculator
- One common mistake to avoid
- One guide worth reading