Investing for Beginners: Your Complete Guide to Getting Started
Investing for Beginners: A Step By Step Guide to Get Started in 2026
Wanting to invest money is one thing, but being successful is a completely different beast. For a beginner, step-one can feel overwhelming due to financial jargon, endless product pitches, and market volatility. However, anyone can invest—it is no longer reserved for wealthy institutional investors or financial experts. View your capital as a tool that, when deployed with discipline, works quietly in the background to build long-term wealth.
Consider this guide your foundational framework. It breaks down the entire process into practical, actionable steps tailored for modern investors: from setting up your baseline personal finances to choosing the right asset classes, understanding tax implications, and avoiding costly beginner mistakes. Regardless of your current income or starting capital, learning how to make your money work for you is a skill within reach.
Why Investing Matters: Beyond Just Making More Money
Growing Your Wealth Over Time:
A common question among beginners is how to move from simply accumulating savings to actively growing wealth. Compounding is the single most powerful driver of long-term financial growth. Investing is like planting a tree: consistent contributions in the early stages provide the baseline, while time and compounding yields significant multi-decade results.
Beating Inflation: Inflation steadily degrades purchasing power. Keeping all your capital in a basic savings account yielding 2.5% to 3.5% per annum means your real purchasing power declines over time after accounting for consumer inflation. Strategic investing across growth-oriented asset classes helps preserve and expand real purchasing power.
Achieving Financial Goals: Whether your objective is purchasing a property, securing a child’s higher education, or target-funding early retirement, structured investing transforms vague goals into precise mathematical milestones.
Financial Security and Independence: An active investment portfolio provides a safety cushion against structural job changes or unexpected family expenses, granting you financial flexibility and peace of mind.
Building the Foundation: 4 Steps Before You Invest
Before buying your first stock or mutual fund, you must establish a stable financial baseline:
1. Assess Your Financial Situation
Track Your Income and Expenses: You cannot invest what you do not track. Use budget management tools, digital expense trackers, or a Microsoft Excel spreadsheet to log your monthly fixed and variable cash outflows.
Create a Balanced Budget: Allocate your take-home pay intentionally. A practical starting framework is The 50/30/20 Rule in India: How to Budget Your Salary, which allocates 50% of net income to essential needs, 30% to discretionary spending, and 20% toward debt payoff and long-term investments.
Build an Emergency Fund First: Never invest capital that you might need for daily survival next month. Build an Emergency Fund Calculator India: How Much Is Your True Safety Net cash cushion covering 3 to 6 months of basic living expenses in liquid instruments like high-yield savings accounts or liquid funds. Having an emergency cushion prevents you from distress-selling equity investments during a market downturn and protects your long-term CIBIL score from forced credit usage.
2. Pay Off High-Interest Consumer Debt
High-interest debt—such as credit card balances carrying annual interest rates of 36% to 42% or costly personal loans—will wipe out potential investment returns. Paying off a 36% credit card bill delivers a guaranteed 36% effective return on your money. Eliminate high-cost debt before committing substantial funds to market investments.
3. Align Goals and Risk Tolerance
Define Specific Timelines: Short-term goals (under 3 years) call for capital preservation assets like fixed deposits or debt mutual funds. Long-term goals (5 to 10+ years) can handle equity market fluctuations in exchange for higher inflation-adjusted growth.
Assess Risk Capacity vs. Risk Appetite: Risk capacity depends on your financial stability, job security, and horizon. A 25-year-old earning a steady salary can easily ride out equity market volatility, whereas an investor nearing retirement requires greater portfolio stability.
4. Educate Yourself on Core Principles
- Core Books: Timeless texts such as The Intelligent Investor by Benjamin Graham and The Psychology of Money by Morgan Housel teach essential behavioral discipline and risk management.
- Regulatory Guidance: Follow official educational frameworks from regulators like SEBI and RBI to avoid unregulated schemes and high-risk speculative traps.
- Structured Content: Utilize reputed financial media and educational tools to learn fundamental balance sheet analysis and economic concepts.
Understanding Investment Options: Your Core Asset Classes
Once your financial baseline is secure, explore the primary tools available in your investment universe:
Stocks (Equities): Direct Company Ownership
Buying individual shares gives you fractional equity ownership in a publicly traded firm. Equities offer strong long-term real return potential but involve short-term market volatility.
- Growth Stocks: Companies reinvesting cash flows to expand revenues rapidly. They often pay minimal dividends but focus on capital appreciation.
- Value Stocks: Established businesses trading at attractive valuations relative to their earnings, book value, or cash flow metrics.
- Dividend Stocks: Cash-generative firms that routinely distribute a portion of profits back to shareholders, providing regular cash inflows.
Fixed Income & Bonds: Lending for Income
Bonds represent debt instruments issued by governments or corporations. In exchange for your capital, the issuer pays periodic interest (coupon) and returns the principal at maturity.
- Government Securities (G-Secs & T-Bills): Sovereign-backed debt backed by the central government, representing low credit risk.
- Corporate Bonds & Fixed Deposits: Debt issued by private or public corporations. They offer higher yield interest rates than G-Secs but carry credit risk depending on the issuer’s credit rating.
Mutual Funds: Professionally Managed Portfolios
Mutual funds pool money from thousands of retail investors to buy a diversified basket of stocks, bonds, or money market securities. Investing via systematic investment plans (SIPs) automates monthly investing and averages out purchase costs over market cycles.
- Equity Funds: Invest primarily in publicly traded shares across market caps (Large-Cap, Mid-Cap, Small-Cap, and Flexi-Cap).
- Debt Funds: Invest in fixed-income securities like commercial paper, certificates of deposit, and corporate debt. (Note: Investors evaluating fixed-income exposure should check whether Should Young Investors in Their 20s and 30s Avoid Debt Mutual Funds? fits their tax slab and overall wealth strategy).
- Index Funds: Passive low-cost funds designed to replicate market indices like the Nifty 50 or S&P 500, keeping expense ratios low.
- Sectoral & Thematic Funds: Specialized funds targeting specific industries. However, data shows that sector timing is difficult—as highlighted in Thematic Mutual Funds 2026: 5 Winning Sectors and Why 80% Have Failed, specialized themes require strict entry and exit discipline.
Exchange-Traded Funds (ETFs)
ETFs function similarly to index mutual funds but trade live on stock exchanges throughout market hours. They offer real-time liquidity, operational flexibility, and typically very low expense ratios.
Real Estate & Digital Real Estate (REITs)
While physical property ownership requires large capital outflows, Real Estate Investment Trusts (REITs) allow retail investors to buy liquid, dividend-yielding shares of commercial real estate portfolios directly on the stock exchange with small investment amounts.
Tax-Advantaged Long-Term Accounts
Take advantage of government-backed retirement and long-term saving schemes available in your country (such as EPF, PPF, or NPS in India, or 401(k) and IRAs in the US) to compound wealth under efficient tax structures.
Building Your Investment Portfolio: Asset Allocation
Diversification is the practice of spreading capital across uncorrelated asset classes to minimize total portfolio risk. Proper asset allocation prevents a sudden drop in one market sector from impairing your entire net worth.
- Strategic Asset Allocation: Divide your portfolio systematically between growth assets (equities) and defensive assets (fixed income, gold) based on your age, financial goals, and emergency cushion.
- Portfolio Rebalancing: Review your asset mix once or twice a year. If strong equity gains expand your stock allocation beyond your baseline target, rebalance by selling a small portion of equities and reallocating to fixed income to maintain your risk balance.
Common Beginner Mistakes to Avoid
- Chasing Unrealistic Returns: Avoid dubious investment platforms promising guaranteed high returns or daily profit returns. Be aware of common red flags covered across cyber fraud investigations.
- Attempting to Time the Market: Trying to predict exact market tops and bottoms leads to missed gains and emotional mistakes. Consistent time in the market outweighs timing the market.
- Ignoring Fees and Expense Ratios: High fund management fees, entry loads, or platform transaction charges quietly compound into significant losses over decades. Opt for direct mutual fund plans and low-cost index ETFs where appropriate.
- Over-Concentration: Putting all your savings into one trending stock, single sector, or single crypto asset exposes you to unrecoverable losses if that asset falters.
How to Take Action: Step-by-Step Implementation
1. Complete Your Onboarding & KYC: Choose a reputable, low-cost broker or investment platform regulated by official market authorities (such as SEBI in India or SEC in the US). Complete your Know Your Customer (KYC) registration using your official identity documents.
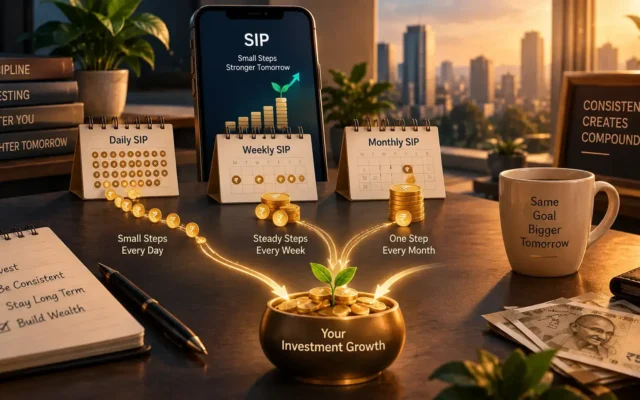
2. Start Small and Automate: Begin with an amount you can comfortably commit every month. Set up an automated standing instruction or monthly SIP from your salary account to remove emotional friction from the process.
3. Review Periodically, Not Daily: Staring at your investment portfolio daily induces unnecessary panic over routine market noise. Schedule structured quarterly or semi-annual portfolio health checks.
4. Keep Upgrading Your Financial Literacy: The investment environment changes over time as tax codes, interest rate regimes, and market regulations evolve. Stay updated through verified financial news sources and standard regulatory updates.
Conclusion: Start Building Your Financial Freedom Today
Investing is a marathon, not a sprint. You do not need a business degree or vast wealth to build a resilient, compounding investment portfolio. By clearing high-cost debt, maintaining an adequate emergency cushion, choosing straightforward index or diversified equity funds, and staying disciplined through market cycles, you take full control of your financial path.
The single most valuable resource in investing is time. Start with whatever small, comfortable amount you have today, maintain continuous learning, and let the math of compounding work for you.
Ready for Your Next Money Step?
See a short list of guides and calculators for starting to invest, in a sensible order, with no sign-up. Projections are estimates, never guarantees, and this is for learning, not personal advice.
This article is for educational purposes only and does not constitute financial advice. Figures, examples, and outcomes are illustrative and vary based on individual circumstances and lender policies. Always consult a certified financial advisor before making major financial decisions.
One Email a Week. Five Things Worth Knowing.
- One important financial change that actually affects you
- One practical money lesson
- One useful calculator
- One common mistake to avoid
- One guide worth reading