Thematic Mutual Funds 2026: 5 Winning Sectors and Why 80% Have Failed
You see the ads everywhere on your phone: defense sector funds surging 60% in a single year, PSU funds doubling money, or green energy themes promising guaranteed multi-bagger wealth for the decade ahead. It feels like easy money. Why settle for a boring flexi-cap fund compounding at 12% to 15% when thematic mutual funds India 2026 are promising rapid 40% returns right now?
It is a psychological trap. You are watching a thematic engine firing at maximum pressure without checking if the tracks end at a cliff edge. Investing in thematic mutual funds India 2026 without understanding business cycles often leads to severe portfolio damage.
The harsh reality is that thematic investing is a high-stakes, cyclical game where timing is everything. Sector trends burn exceptionally hot, draw in billions of retail rupees at the exact market peak, and then cool off into brutal multi-year drawdowns that wreck portfolios. If you do not know precisely when to enter and when to run for the exit, thematic mutual funds India 2026 will turn your hard-earned wealth into an expensive lesson in market over-concentration.
In this comprehensive guide, we unpack the stark reality behind thematic mutual funds India 2026. We will look at real portfolio data, highlight which rare sectors are still delivering profits, analyze the systemic reasons behind widespread sector fund crashes, and show you exact step-by-step strategies to protect your capital. Navigating thematic mutual funds India 2026 requires strict emotional discipline and clear position limits.
Key Takeaways
- Brutal Cyclicality: Thematic funds experience massive boom-and-bust cycles where top-performing themes routinely drop 30% to 50% during sector turnarounds.
- The Timing Trap: Over 80% of retail money flows into thematic funds near their peak valuation, locking investors into years of flat or negative returns.
- Core vs. Satellite: Allocations to thematic mutual funds India 2026 should never exceed 10% to 15% of your total equity portfolio; they belong strictly in your satellite allocation.
- Active Sectors in 2026: Manufacturing, defense, and specialized banking represent strong structural tailwinds, while overhyped niche sectors are running on dangerous valuations.
- Strict Exit Rules: Unlike diversified equity funds that you hold for decades, thematic funds require automated stop-loss triggers and strict profit-taking targets.
The Great Sector Trap: Why Most Thematic Mutual Funds Fail
To understand why thematic mutual funds India 2026 are inherently risky, you must first understand how fund houses manufacture them. Asset Management Companies (AMCs) are businesses. They launch thematic funds not when a sector is at its bottom valuation, but when public excitement reaches a fever pitch. By the time a fund house files a new fund offer (NFO) for a specific theme, the underlying stocks have likely already experienced a massive run-up. Evaluating thematic mutual funds India 2026 during peak media hype almost always leads to buying at elevated price levels.
Retail investors see stellar 1-year trailing returns in marketing brochures and jump in with massive lump-sum investments. Shortly after, the sector peaks, money flows out, and those trailing returns evaporate into thin air.
The Destruction of Retail Capital in Hype Cycles
Consider what happened during the infrastructure boom of 2007. Retail investors poured tens of thousands of crores into infrastructure sector funds right before the global financial crisis hit. When the market crashed, those funds plummeted by 60% to 70%. More critically, while broader market indices recovered and broke new all-time highs within a few years, many specialized infrastructure funds took over a decade just to return to their original net asset value (NAV).
The exact same structural pattern repeated in IT funds post-2021 and pharma funds post-COVID. When a single narrative drives a cluster of stocks, valuation rules get thrown out the window until reality hits. Understanding Is This Investment Return Too Good to Be True? is crucial before you buy into any fund promising returns far above baseline equity averages. Watching how thematic mutual funds India 2026 behave during sector corrections reveals the danger of relying on historical momentum.
Over-Concentration vs True Diversification
A standard flexi-cap or multi-cap fund holds 50 to 80 stocks spread across banking, IT, consumer durables, automobiles, and pharmaceuticals. If regulatory guidelines set by SEBI hit the banking sector, the automobile or IT allocation absorbs the shock and keeps your portfolio steady.
A thematic fund throws that diversification safety net out the window. If you buy an EV and green mobility fund, you are heavily concentrated in a tight basket of auto ancillary, battery manufacturer, and chemical companies. When raw material costs spike or government subsidies taper off, every single stock inside that fund falls simultaneously. There is simply no safe harbor within a single-theme portfolio when the macroeconomic cycle turns against thematic mutual funds India 2026.
Analyzing Thematic Performance in 2026: Winners vs Trap Sectors
Not all thematic mutual funds India 2026 are created equal. Some themes are driven by transient market sentiment, while others are supported by massive public spending, long-term policy shifts, and balance sheet growth. Let us analyze where major sector categories stand right now.
1. Indian Manufacturing and Infrastructure Funds
The structural push for domestic manufacturing under production-linked incentive (PLI) schemes has provided real order book visibility for capital goods, engineering, and infrastructure companies. Funds in this sector have shown solid multi-year earnings growth rather than purely speculative price spikes.
However, valuations in capital goods are stretched well above their 10-year historical average price-to-earnings ratios. While the long-term structural theme remains robust, fresh allocation via large lump-sum investments into manufacturing-focused thematic mutual funds India 2026 is extremely dangerous. Systematic investment plans (SIPs) or gradual rupee-cost averaging are the only prudent ways to gain exposure here.
2. Defense and Public Sector Undertaking (PSU) Themes
PSU and defense themes were the star performers leading into 2026, delivering jaw-dropping returns that captured headlines across financial news platforms. Government defense indigenization policies turned balance sheets around for defense manufacturing entities, clearing decades of inefficiency.
The trap now is price fatigue. Much of that future earnings visibility is already priced in for the next 3 to 5 years. Investors entering these thematic mutual funds India 2026 today purely looking at 3-year trailing performance figures face severe valuation compression risks if quarterly order execution slows down even slightly.
3. Banking and Financial Services (BFSI) Funds
Banking is the ultimate structural backbone of the Indian economy. Unlike narrow niche themes, BFSI encompasses private banks, public sector banks, NBFCs, housing finance firms, credit card providers, and insurance companies. Because the financial services ecosystem is diverse, BFSI funds behave far more like core market sector funds than volatile thematic plays.
With clean corporate balance sheets, low non-performing assets (NPAs), and steady credit growth regulated by RBI, banking sector funds present a durable medium-term outlook. However, keep in mind that any multi-cap or large-cap fund you already own is likely sitting on a 25% to 35% exposure to financial services already. Buying dedicated thematic mutual funds India 2026 in the BFSI segment often results in massive portfolio overlap.
4. Technology and Digital Innovation Themes
IT sector funds have experienced extreme volatility. After soaring during the global digital transformation surge, IT funds faced multi-year stagnation as western enterprise software spending slowed down under high interest rates. In 2026, technology funds are attempting to pivot toward AI integration, global capability centers (GCCs), and domestic digital platforms.
While long-term tech tailwinds are indisputable, short-term earnings volatility remains high. Tech-focused thematic mutual funds India 2026 are suitable only for patient capital willing to sit through 3-year periods of absolute sideways movement before the next enterprise spending wave kicks in.
5. Green Energy and EV Transition Funds
Green energy, solar equipment, and electric vehicle value-chain funds were launched with massive marketing hype. While the multi-decade transition away from fossil fuels is non-negotiable, many listed companies in this ecosystem trade at sky-high price-to-earnings multiples despite generating razor-thin profit margins.
Regulatory tweaks, technological disruption, and intense foreign competition make green energy a tricky thematic path. Investing in these thematic mutual funds India 2026 remains a high-risk, speculative satellite bet that can suffer severe drawdowns during commodity price shocks.
The Cold Math: How Thematic Cycles Destroy Multi-Year Returns
To truly grasp the mechanical risk of thematic mutual funds India 2026, you must look at real numbers. Let us walk through a concrete scenario illustrating how a thematic crash decimates portfolio math compared to a steady, diversified broad-market fund.
Consider standard investment outcomes for a thematic fund versus a broad market index like the Nifty 50 over a volatile 5-year sector cycle.
| Year / Metric | Thematic Sector Fund (Hype to Crash) | Diversified Broad Market Fund |
|---|---|---|
| Year 1 Return | +50.0% (Massive Sector Rally) | +12.0% (Steady Growth) |
| Year 2 Return | +30.0% (Peak Retail Entry) | +10.0% (Consistent Progress) |
| Year 3 Return | -40.0% (Sector Bubble Bursts) | -8.0% (Mild Correction) |
| Year 4 Return | -15.0% (Continued Drawdown) | +15.0% (Market Recovery) |
| Year 5 Return | +10.0% (Slow Stagnant Recovery) | +12.0% (Normal Expansion) |
| Ending Value (₹100,000 Invested) | ₹102,321 | ₹147,153 |
| 5-Year CAGR | 0.46% (Capital Stagnation) | 8.03% (Wealth Compounded) |
Look at those numbers carefully. In Year 1 and Year 2, the thematic fund was the absolute star of social media finance forums, delivering a cumulative surge that turned head after head. But the mathematics of a 40% crash followed by a 15% drop requires a massive 100%+ gain just to break even. An investor in thematic mutual funds India 2026 during a downturn effectively locks up ₹1,00,000 for half a decade to earn a miserable 0.46% annualized return, completely failing to beat inflation.
Meanwhile, the “boring” broad market fund steadily compounded wealth, avoiding catastrophic drawdowns and leaving the thematic investor far behind in actual cash terms.
Case Study: Rajesh’s ₹10 Lakh PSU Thematic Bet
Let us look at a real-world scenario. Meet Rajesh, a 34-year-old IT manager based in Bengaluru earning ₹1.8 lakh per month. In late 2023, after seeing screens of staggering 1-year returns on social media, Rajesh decided to reallocate ₹10 lakh from his fixed deposits and low-volatility portfolio into a newly launched PSU and capital goods thematic fund.
For the first six months, Rajesh felt like an investing genius. His portfolio value climbed up to ₹12.5 lakh. Emboldened by these quick gains, he stopped his disciplined monthly SIP in a broad multi-cap index and diverted all excess surplus into thematic mutual funds India 2026.
Then, the market cycle shifted. In mid-2024, order execution delays hit key infrastructure suppliers, foreign institutional investors pulled capital from expensive valuation pockets, and government spending growth temporarily slowed during election adjustments. Over the next nine months, the PSU thematic fund dropped 32% from its peak.
Rajesh’s ₹12.5 lakh portfolio shrank rapidly down to ₹8.5 lakh. Panic set in. Unable to bear the emotional pain of seeing his capital erode, Rajesh redeemed his remaining units at a net loss of ₹1.5 lakh compared to his principal. Had he simply maintained his core allocation in broad market equity or balanced options, his capital would have continued its upward path uninterrupted.
Rajesh’s story is not unique; it is the standard journey for millions of retail investors who treat thematic mutual funds India 2026 as quick wealth shortcuts rather than volatile tactical instruments.
How Regulator Norms and AMC Marketing Push You into Sector Schemes
To navigate thematic mutual funds India 2026 safely, you must see through the institutional dynamics that push these products onto your screen. Regulatory bodies like SEBI maintain strict categorization rules for mutual funds. Under these guidelines, an AMC can offer only one large-cap fund, one mid-cap fund, one small-cap fund, and one flexi-cap fund.
So how does a mutual fund company grow its Assets Under Management (AUM) and earn more management fee revenue once its broad equity fund slots are full? Simple: by launching thematic and sector funds.
There is no cap on the number of thematic or sector schemes an AMC can launch. Whether it is healthcare, defense, manufacturing, digital services, or business cycles, fund houses can create an endless pipeline of specialized thematic products. When a specific industry garners public news coverage, the AMC launches a corresponding fund to capture retail capital inflows. The system is mechanically incentivized to sell you thematic mutual funds India 2026 when public interest is high, regardless of whether it makes long-term investment sense for your financial goal.
The Core-Satellite Portfolio Framework: Where Do Thematics Fit?
Does this mean you should completely avoid thematic mutual funds India 2026? Not necessarily. Thematic funds can serve a purposeful function, provided you use them as tactical wealth enhancers rather than foundational savings tools.
Smart portfolio design relies on the Core-Satellite Model.
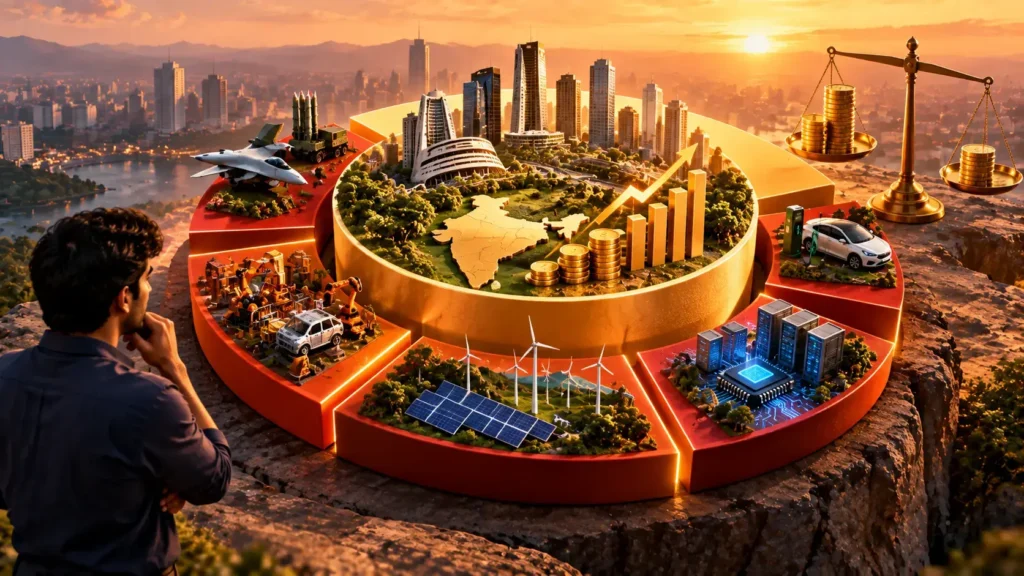
1. The Core Portfolio (80% to 90% Allocation)
Your core portfolio handles the heavy lifting for your critical life goals—your retirement, long-term wealth accumulation, and your children’s higher education funding. This core allocation must consist exclusively of broad, diversified market equity funds:
- Flexi-Cap / Multi-Cap Funds
- Large & Mid-Cap Funds
- Broad Market Index Funds (Nifty 50, Nifty LargeMidcap 250)
These broad categories automatically rebalance across sectors behind the scenes. If banking slows down and manufacturing surges, a professional flexi-cap fund manager shifts capital dynamically inside the fund without creating a capital gains tax event for you. If you are building a foundational portfolio, mastering The 50/30/20 Rule in India: How to Budget Your Salary will help you generate the baseline savings needed to fund a resilient core portfolio first.
2. The Satellite Portfolio (10% to 15% Maximum Allocation)
Your satellite portfolio is designed for high-risk, high-alpha tactical bets. This is where a small, deliberate allocation to thematic mutual funds India 2026 belongs. If a tactical sector theme drops 40%, the maximum damage to your overall wealth is limited to 4% to 6% of your aggregate portfolio—an amount your core holdings can easily absorb through routine compounding.
If you choose to run a satellite thematic allocation, follow these strict execution rules:
- Cap individual sector exposure at 5%: Never put more than 5% of your total net worth into thematic mutual funds India 2026 within a single sector.
- Set absolute return targets: Unlike index funds that you hold forever, thematic bets require profit targets. If a theme surges 40% in a year, systematically rebalance profits back into your core index or flexi-cap holdings.
- Avoid duplicate holdings: Before buying a sector fund, inspect your existing flexi-cap holdings using fund overlap calculators. If your flexi-cap fund already holds 30% financial stocks, adding dedicated thematic mutual funds India 2026 in banking creates excessive, hidden portfolio risk.
Evaluating Debt Alternatives vs Thematic Risk
When investors get frustrated by high stock valuations or thematic volatility, they often swing to the opposite extreme, placing money into debt instruments without clear strategy. Understanding fixed income mechanics and yield shifts monitored by the RBI is critical for maintaining overall balance across market cycles.
While thematic equity funds sit on the extreme end of the risk spectrum, debt funds offer capital preservation and predictable yield. However, tax changes introduced under recent financial regulations mean debt mutual funds no longer enjoy long-term indexation benefits. Returns are now added directly to your taxable income slab.
If you are reallocating capital away from high-volatility thematic mutual funds India 2026 to stabilize your broader wealth, evaluate debt mutual fund mechanics carefully. High-earning investors must weigh taxation and interest rate cycles when balancing stability against growth. For a detailed breakdown of how fixed-income strategies fit into modern portfolios, read Should Young Investors in Their 20s and 30s Avoid Debt Mutual Funds? to make an informed choice.
Step-by-Step Execution: How to Handle Existing Thematic Funds
What should you do if you are currently holding underperforming or over-concentrated thematic mutual funds India 2026? Follow this practical decision tree to clean up your portfolio.
Step 1: Check Portfolio Overlap and Aggregate Exposure
Consolidate your mutual fund statements using CAMS or KFintech CAS reports. Calculate the total market value of all thematic mutual funds India 2026 in your portfolio. If thematic funds account for more than 15% of your total equity capital, you are over-exposed and need to trim your holdings.
Step 2: Evaluate Sector Earnings Visibility
For each thematic fund you hold, look beyond trailing returns and examine the underlying sector’s underlying earnings growth. Ask two simple questions:
- Are the underlying sector companies showing revenue and profit growth over recent quarters?
- Is the stock price appreciation backed by actual earnings, or purely by valuation multiple expansion?
If a sector’s profits are stagnant while its valuation multiples have doubled, exit your thematic mutual funds India 2026 and reallocate capital into broad-market index funds or flexi-cap options.
Step 3: Implement Systematic Transfer Plans (STP) for Profit Taking
If you are sitting on substantial gains in a high-performing theme like manufacturing or defense, do not wait for the inevitable sector downturn to wipe out your profits. Initiate a Systematic Transfer Plan (STP) or set up monthly redemptions to move gains out of thematic mutual funds India 2026 and into a low-volatility broad index fund or liquid fund over 6 to 12 months.
This automated strategy locks in real returns while ensuring you do not trigger massive lump-sum exit loads or short-term capital gains tax spikes needlessly.
4 Essential Checks Before Buying Any Thematic Fund in 2026
Before you tap “Invest Now” on any sleek mutual fund app advertising thematic mutual funds India 2026, run through this simple 4-step sanity checklist:
Try it yourself on your current portfolio app:
- The Trailing Return Test: Am I buying this fund because I genuinely understand the 5-year underlying sector economy, or simply because its 1-year trailing return box is highlighted in green? If your answer is trailing returns, close the app immediately.
- The 5-Year Lock Horizon Test: Am I prepared to see thematic mutual funds India 2026 trade completely sideways or stay down by 30% for 3 to 5 years without panicking? If your financial goal is less than 5 years away, thematic funds are completely off-limits.
- The Portfolio Concentration Check: Will this purchase push my total thematic sector exposure past 15% of my overall liquid equity portfolio? If yes, trim existing positions before adding new ones.
- The Exit Strategy Requirement: Have I defined an exact profit target (e.g., rebalancing once the fund hits a 30% gain) and a stop-loss threshold? Holding thematic mutual funds India 2026 without an exit plan is pure gambling.
FAQs
What is the main difference between sector funds and thematic funds in India?
Sector funds invest tightly within a single defined industry like banking, pharmaceuticals, or technology. Thematic funds hold a broader mandate, investing across multiple industries linked by a single underlying trend, such as an infrastructure theme holding banks, cement manufacturers, and engineering firms simultaneously.
Are thematic mutual funds suitable for first-time retail investors?
No, first-time investors should strictly avoid thematic mutual funds India 2026. Beginners need the structural stability and multi-sector protection of broad-market options like flexi-cap or low-cost index funds to build wealth consistently without being scared away by severe drawdowns.
How much allocation should thematic mutual funds India 2026 have in my portfolio?
Thematic funds should never exceed 10% to 15% of your total equity portfolio. Treat thematic mutual funds India 2026 strictly as high-risk, high-alpha satellite bets while keeping 85% to 90% of your wealth in core, broad-market diversified equity funds.
How are returns from thematic mutual funds taxed in India?
Equity-oriented thematic funds (holding over 65% domestic equity) follow standard equity taxation rules established under Indian tax law. Gains on units held for less than 12 months incur Short-Term Capital Gains (STCG) tax at applicable rates, while gains held over 12 months trigger Long-Term Capital Gains (LTCG) tax on returns exceeding standard annual exemption limits. Check current tax rules for precise details during your filing year.
Final Thoughts
Thematic mutual funds India 2026 offer an alluring proposition: the promise of market-beating alpha by capturing high-growth industrial trends. But market math is unflinching. The extreme volatility, over-concentration risks, and poor retail entry timing mean that the vast majority of investors end up earning lower returns in sector funds than they would have in a simple, boring flexi-cap index.
Stop chasing rear-view mirror returns. Treat thematic mutual funds India 2026 as what they truly are—tactical, high-maintenance instruments that belong on the small outer edges of your portfolio, not at its center. Focus your primary energy on compounding baseline wealth through disciplined monthly SIPs in broad-market funds, control your portfolio asset allocation, and leave high-stakes sector timing games to institutional traders who can afford the losses.
Take control of your portfolio today: run an overlap check on your current mutual fund holdings, identify any hidden sector concentration risks, and start trimming your thematic mutual funds India 2026 exposure down to safe core-satellite boundaries.
This article is for educational purposes only and does not constitute financial advice. Figures, examples, and outcomes are illustrative and vary based on individual circumstances and lender policies. Always consult a certified financial advisor before making major financial decisions.
One Email a Week. Five Things Worth Knowing.
- One important financial change that actually affects you
- One practical money lesson
- One useful calculator
- One common mistake to avoid
- One guide worth reading