Home Loan EMI Calculator India: 7 Proven Checks Before You Borrow
Your bank says the EMI is manageable. The builder wants the booking amount. And the difference between two lenders looks like just 0.5%. That small-looking gap can cost you several lakhs over a long home loan.
A home loan EMI calculator India can show the monthly payment, but a useful decision takes more than one number. You need to compare the same loan amount and tenure, understand how floating rates may change, and check whether the EMI still leaves room for the rest of your life.
This guide gives you the formula, a fully worked comparison, practical checks before you sign, and a clear way to use a calculator without mistaking an estimate for a promise.
Key Takeaways
- A 0.5 percentage-point rate difference on a ₹50 lakh loan over 20 years can change total interest by about ₹3.8 lakh, before fees or future rate resets.
- The standard EMI formula uses principal, monthly interest rate and number of monthly payments. Keep those inputs identical when comparing lenders.
- A home loan EMI calculator India estimates a payment; it does not decide your eligibility or guarantee the final rate.
- Longer tenure lowers the EMI but usually increases total interest substantially.
- For a floating-rate loan, understand the lender’s reset frequency and whether a rate change affects EMI, tenure or both.
- Check affordability against take-home pay, existing EMIs, maintenance, insurance and an emergency buffer—not just the bank’s maximum offer.
What a home loan EMI calculator India actually tells you
EMI is principal plus interest in one monthly payment
EMI means equated monthly instalment. Each payment includes interest on the outstanding loan and a portion that repays principal. Early in a long loan, the interest portion is larger because the balance is still high. As the balance falls, more of each payment goes toward principal.
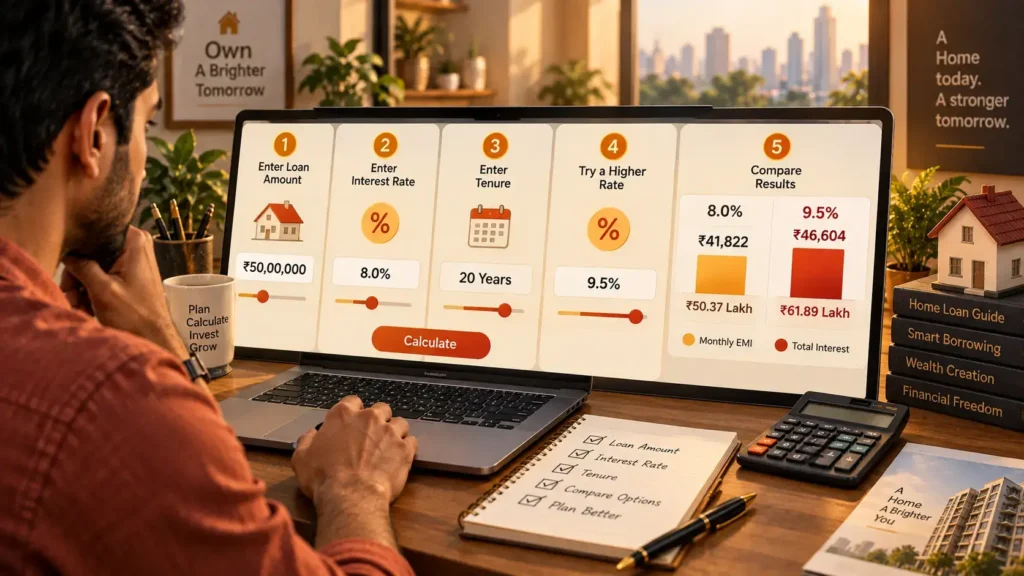
A home loan EMI calculator India typically asks for three inputs: loan amount, annual interest rate and tenure. It then estimates the monthly payment and often the total interest and total amount paid. That is useful—but it is not a sanction letter, a final rate quote or a full affordability assessment.
Understand what the calculator leaves out
Ravi, a software employee in Hyderabad, enters a ₹50 lakh loan, a 9% annual rate and a 20-year tenure. His result is an estimated EMI. It will not automatically include processing charges, legal and valuation costs, property registration expenses, home insurance, society maintenance or the cash he needs for interiors after possession.
A home loan EMI calculator India is most useful when you treat its result as one part of a complete home-buying budget. Those costs do not all belong inside the EMI calculation. They still belong in the home-buying budget. If Ravi uses the calculator’s EMI as his entire monthly housing cost, he has built his plan on an incomplete number.
Try it yourself: enter the loan amount you are actually likely to borrow—not the property’s full price—and use the rate and tenure written in the lender’s offer. Save the result. Then repeat with a rate 0.5 percentage points higher.
How to calculate home loan EMI: the formula and a worked example
The formula behind the monthly figure
The standard reducing-balance EMI formula is: EMI = P × r × (1 + r)n ÷ [(1 + r)n − 1]. P is the principal borrowed, r is the monthly interest rate expressed as a decimal, and n is the total number of monthly payments.
Convert the annual rate into a monthly rate by dividing it by 12 and then by 100. For a 9% annual rate, r = 9 ÷ 12 ÷ 100 = 0.0075. A 20-year loan has n = 20 × 12 = 240 monthly payments. Keep the rate and tenure in matching units; entering 9 instead of 0.0075 as the monthly rate will give nonsense.
Compare 8.5% with 9% on ₹50 lakh
Take Ravi’s ₹50 lakh principal and 20-year tenure. Assume the rates stay unchanged throughout the loan purely for this illustration. In real life, a floating rate may change, so the final amount can differ.
| Annual rate | Estimated EMI | Total paid over 20 years | Estimated total interest |
|---|---|---|---|
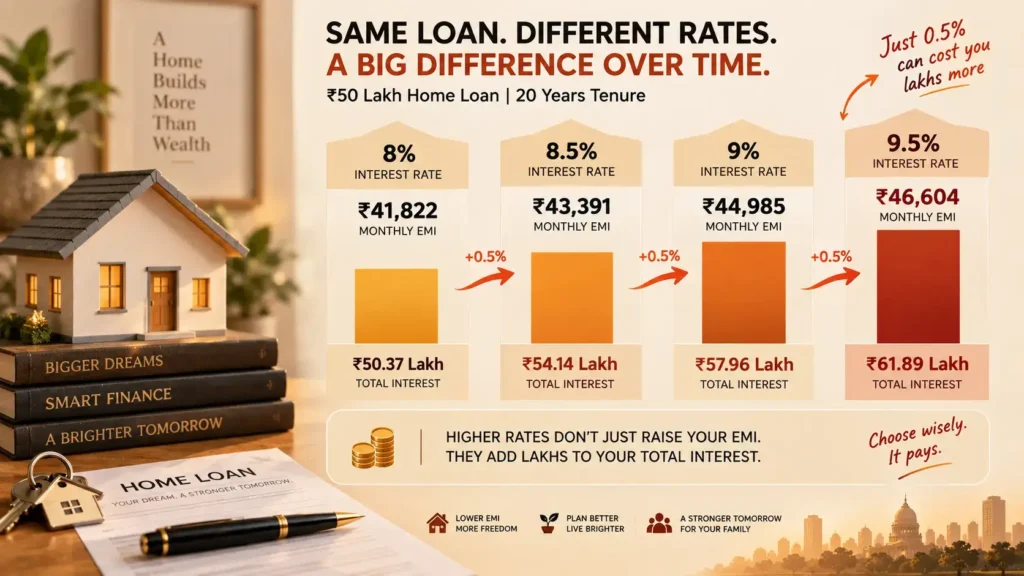
| 8.5% | About ₹43,400 | About ₹1,04,15,000 | About ₹54,15,000 |
| 9.0% | About ₹44,990 | About ₹1,07,98,000 | About ₹57,98,000 |
| Difference | About ₹1,590 more per month | About ₹3,83,000 more | About ₹3,83,000 more |
The higher rate adds roughly ₹1,590 to the monthly payment and about ₹3.8 lakh to the total interest under these assumptions. That is the real weight of a half-point difference. It is not a rounding error.
Try it yourself: use a home loan EMI calculator India and enter ₹50,00,000, 20 years, then 8.5% and 9% separately. Your calculator may show a small difference in rounding. Compare total interest as well as EMI; the monthly figure alone hides the long-term cost.
Why the same rate gap costs more on a bigger or longer loan
Interest applies to the outstanding balance over time. A larger principal gives the rate more rupees to work on. A longer tenure gives interest more months to accumulate. So a 0.5-point difference can cost more on a ₹75 lakh loan over 25 years than it does on ₹50 lakh over 20 years.
Do not treat the ₹3.8 lakh example as a universal answer. Your principal, tenure, repayment schedule and future rate movements change the result. The home loan EMI calculator India gives you a scenario, not a fixed prediction of every rupee you will pay.
How to compare two bank offers without being misled
Put both offers on the same footing
Meera, a teacher in Pune, is offered ₹60 lakh by two lenders. One quotes a lower rate but a shorter tenure in its illustration; the other shows a longer tenure and a lower EMI. Comparing those two EMIs would tell her very little. She must compare the same principal, same tenure and same repayment assumptions first.
Use a home loan EMI calculator India to make that like-for-like comparison. Then review the written offer for the rate type, fees and conditions. A headline rate is only one part of the borrowing cost.
| What to compare | What to check in the offer | Why it matters |
|---|---|---|
| Interest rate | Floating or fixed, and the applicable benchmark or reset terms | A quoted rate may change under the loan agreement. |
| Processing and other charges | Processing, legal, technical valuation and documentation charges | Upfront costs can narrow the advantage of a lower rate. |
| Tenure and EMI | Same tenure and principal in each comparison | A smaller EMI may simply mean you repay for longer. |
| Part-prepayment terms | How extra payments are treated and any applicable conditions | Flexibility can matter if your income rises or you receive a bonus. |
| Reset details | How often a floating rate is reviewed and how changes are applied | Rate changes can affect your monthly payment or loan end date. |
Look beyond the EMI to the total borrowing cost
Ask each lender for a written list of charges and the repayment schedule. Clarify which costs are mandatory, which are optional and when they are payable. A ₹20,000 difference in fees does not automatically outweigh a rate advantage worth several lakhs—but ignoring fees means you do not know the real comparison.
Also check whether a low initial rate is conditional on a specific product, salary account or other requirement. Don’t assume a verbal assurance will override the loan documents. Read the terms that will govern the account after disbursal.
If you already have a loan and are considering shifting it, include foreclosure or transfer-related costs, fresh processing charges and the remaining tenure. A rate cut on paper can be a poor deal if you refinance late in the loan and pay significant costs to do it.
Floating rates, resets and what happens when rates move
Your EMI estimate may not stay unchanged
Many home loans have floating rates. If the applicable rate changes, the lender may adjust the EMI, the remaining tenure, or a combination, according to the loan terms and applicable process. Ask your lender which approach applies and how you will be notified. Do not assume a calculator’s 20-year result is a promise that the debt ends in exactly 240 payments if the rate changes.
For example, Neha in Chennai starts with a ₹45 lakh floating-rate loan. Her home loan EMI calculator India shows an estimated payment using the rate quoted today. If rates rise later and her EMI stays similar, the remaining tenure may stretch. If the lender raises her EMI instead, her monthly budget takes the hit. Either way, the change has a cost.
Stress-test before you sign
Run at least three scenarios: the rate in the offer, 0.5 percentage points above it and 1 percentage point above it. You are not predicting future rates. You are checking whether your household can absorb a plausible payment shock without turning every unexpected bill into credit-card debt.
Try it yourself: record the EMI at the quoted rate and at +0.5% and +1%. If the higher-rate EMI leaves no room for essential expenses, reduce the loan amount, consider a larger down payment only if it does not wipe out your safety net, or reassess the property budget.
Get the lender to explain the reset frequency and the options available when a rate changes. For current rules and lender-specific processes, check the documents you receive and current information from RBI where relevant. The contract and the applicable rules matter more than a sales conversation.
Can you afford the EMI without making the rest of life fragile?
Start with take-home pay, not the bank’s maximum eligibility
A bank’s eligibility calculation answers whether it may lend to you under its assessment. It does not answer whether the payment feels comfortable after groceries, school fees, medical costs, transport, existing loans and savings. Your approval ceiling is not your personal target.
Suppose Arjun and Kavya bring home ₹1,40,000 a month in Bengaluru. They already pay ₹12,000 toward a car loan and spend ₹35,000 on groceries, transport, utilities and other essentials. A proposed home-loan EMI of ₹55,000 might appear possible on a calculator, but they also need to budget for maintenance, property costs, childcare and savings. They should test the full household cash flow, not just ask whether ₹55,000 can be debited.
Include costs that arrive outside the EMI
Build a monthly housing estimate that includes EMI, society maintenance, property tax where applicable, home insurance if chosen, commuting changes and a provision for repairs. Some expenses are annual or occasional rather than monthly. Divide predictable annual costs by 12 for planning, but keep enough cash available when the actual bill arrives.
Also protect your emergency savings. Using every rupee for a down payment can leave you vulnerable to a job disruption, medical expense or a repair just after possession. A home is not financially secure if one unexpected bill forces you to borrow at a high rate.
Use How to Budget on a Rs. 30,000 Monthly Salary in India as a practical reminder that a budget must account for real household spending, not just headline income. If the payment only works when nothing goes wrong, it does not work.
Tenure, down payment and prepayment: the levers you control
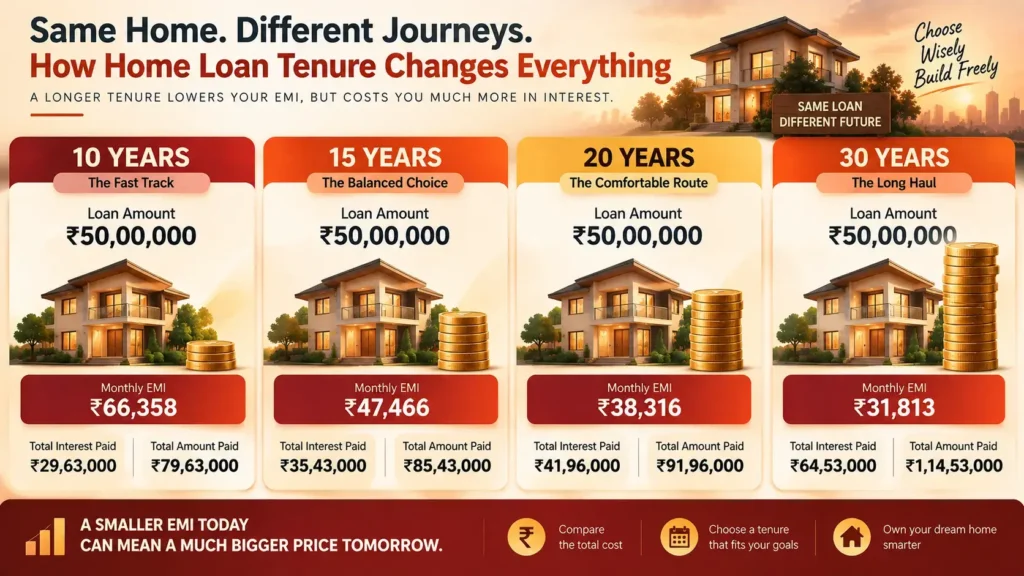
A longer tenure lowers the EMI but raises the lifetime bill
Stretching a loan from 20 to 25 years can make the monthly EMI look friendlier because you spread repayment over more months. But the balance stays outstanding for longer, so total interest can rise sharply. Ask the calculator to show both EMI and total interest for each tenure before deciding.
For instance, Sandeep in Jaipur compares the same ₹50 lakh loan at the same assumed rate over 20 and 25 years. The 25-year option may free up monthly cash, but it commits him to five additional years of payments and more interest if he follows the schedule. If he chooses the longer tenure for flexibility, he should have a realistic plan for prepayments rather than assuming he will somehow make them later.
A bigger down payment has an opportunity cost
A larger down payment reduces the principal and usually reduces the EMI and interest burden. But do not empty emergency savings or sell long-term investments without considering what you give up. The right down payment is not automatically the largest amount you can assemble; it is an amount that keeps both the loan and your cash reserves manageable.
Compare the cost of borrowing with the value of retaining accessible savings, while being honest about risk. A guaranteed loan cost and a hoped-for investment return are not interchangeable numbers. If you are comparing loan prepayment with investing, the InvestingLens article Should I Prepay My Home Loan or Invest the Extra? Here’s the Real Math can help frame the trade-off rather than assuming one choice always wins.
Make prepayments deliberately
When you pay extra toward principal, ask the lender to confirm how it will be applied and whether you can choose a reduced tenure, reduced EMI or another option under your terms. Reducing tenure generally keeps the payment effort high and can cut interest faster; reducing EMI may be useful if monthly cash flow is tight. Get the effect in writing or request an updated repayment schedule.
Try it yourself: compare your scheduled payment with a modest extra amount you could reliably pay each year. Do not enter a bonus you may not receive or money already earmarked for taxes, school fees or emergencies. A small repeatable prepayment is better than an ambitious plan that collapses after one year.
Use this home loan EMI calculator India checklist before applying
Gather the right numbers first
A calculator is only as useful as the inputs you give it. Before you open one, collect the likely loan principal, quoted annual rate, proposed tenure and any lender-specific repayment assumptions. If you are comparing lenders, use the same principal and tenure for each quote.
When you use a home loan EMI calculator India, keep a record of the assumptions alongside each result so you can revisit the comparison if an offer changes.
- Loan principal: calculate the amount you need to borrow after the planned down payment.
- Interest rate: use the rate actually quoted to you, and note whether it is fixed or floating.
- Tenure: enter years consistently and convert to months for the formula.
- Stress rates: repeat the calculation at +0.5 and +1 percentage point.
- Upfront costs: list charges separately so they are not mistaken for part of the EMI.
- Household budget: test the payment against actual take-home income and existing obligations.
Read the result like a decision, not a verdict
A home loan EMI calculator India should help you ask better questions: What happens if the rate rises? How much more interest does five extra years add? Is a lower EMI coming from a smaller principal or simply a longer tenure? What cash remains after the down payment and transaction costs?
Check the figures against the lender’s official repayment schedule before accepting an offer. Differences may come from rounding, a different rate convention, disbursal timing or lender-specific calculations. If the number matters to your decision, ask the lender to explain it rather than guessing.
Keep a copy of each scenario. A simple note with lender, rate, tenure, estimated EMI, total interest and charges prevents a common mistake: remembering only the lowest monthly figure after several sales calls.
Common calculator mistakes that distort the answer
Comparing different tenures or loan amounts
If one result uses ₹50 lakh over 20 years and another uses ₹50 lakh over 25 years, the EMI comparison does not isolate the interest rate. Make the inputs identical before attributing a difference to the lender’s price. Then run separate tenure scenarios to understand the trade-off.
Forgetting that annual and monthly rates are different
The formula needs the monthly rate. An annual rate of 8.5% becomes 0.085 ÷ 12 per month, not 8.5 as a decimal monthly input. Most online tools convert this for you, but check how the fields are labelled. One wrong unit can make a reasonable loan look impossible—or the reverse.
Treating a floating-rate estimate as fixed for decades
A result that holds the rate constant is a helpful baseline, not a forecast. Your lender’s reset method, the rate path and any repayments you make affect the eventual schedule. Use the home loan EMI calculator India to stress-test, and revisit the numbers if your rate or income changes.
Finally, do not judge the loan only by whether the EMI is below a round percentage of your income. Household costs differ. A family supporting parents, paying school fees and carrying a car loan has a different safe limit from a single borrower with no dependants and substantial savings.
FAQs
How much EMI will I pay on a ₹50 lakh home loan?
At an assumed 9% annual rate over 20 years, the estimated EMI is about ₹44,990 a month. Your lender’s rate, tenure and repayment terms can change the result.
How much difference does a 0.5% home loan rate change make?
On ₹50 lakh over 20 years, moving from an assumed 8.5% to 9% raises the estimated EMI by about ₹1,590 and total interest by roughly ₹3.8 lakh if the rate stays unchanged.
Does a home loan EMI calculator include processing fees?
Usually, a basic calculator estimates principal and interest payments only. Check fees separately and include them in your total borrowing-cost comparison.
Should I choose a longer tenure to reduce my home loan EMI?
A longer tenure can reduce the monthly payment, but it usually increases total interest. Compare both numbers and choose a tenure that fits your budget without relying on uncertain future prepayments.
Can my home loan EMI change after I take a floating-rate loan?
Yes, a rate change may affect your EMI, tenure or both, depending on your loan terms and lender process. Ask how resets work before signing and review any revised repayment schedule.
Final Thoughts
A home loan is too large a commitment to choose by comparing two EMI screenshots. Put the same principal and tenure into your calculations, test a 0.5% rate increase, add the costs outside the EMI, and make sure your household can handle the payment without draining its safety net.
Your next step: get written offers from at least two lenders, enter their figures into a home loan EMI calculator India, and compare total interest and charges alongside the monthly payment. If the higher-rate scenario breaks your budget, borrow less or revisit the property price before you sign. A home should give you stability—not a monthly financial emergency.
This article is for educational purposes only and does not constitute financial advice. Figures, examples, and outcomes are illustrative and vary based on individual circumstances and lender policies. Always consult a certified financial advisor before making major financial decisions.
One Email a Week. Five Things Worth Knowing.
- One important financial change that actually affects you
- One practical money lesson
- One useful calculator
- One common mistake to avoid
- One guide worth reading