El Niño and Your Monthly Budget: 7 Real Money Pressures to Watch
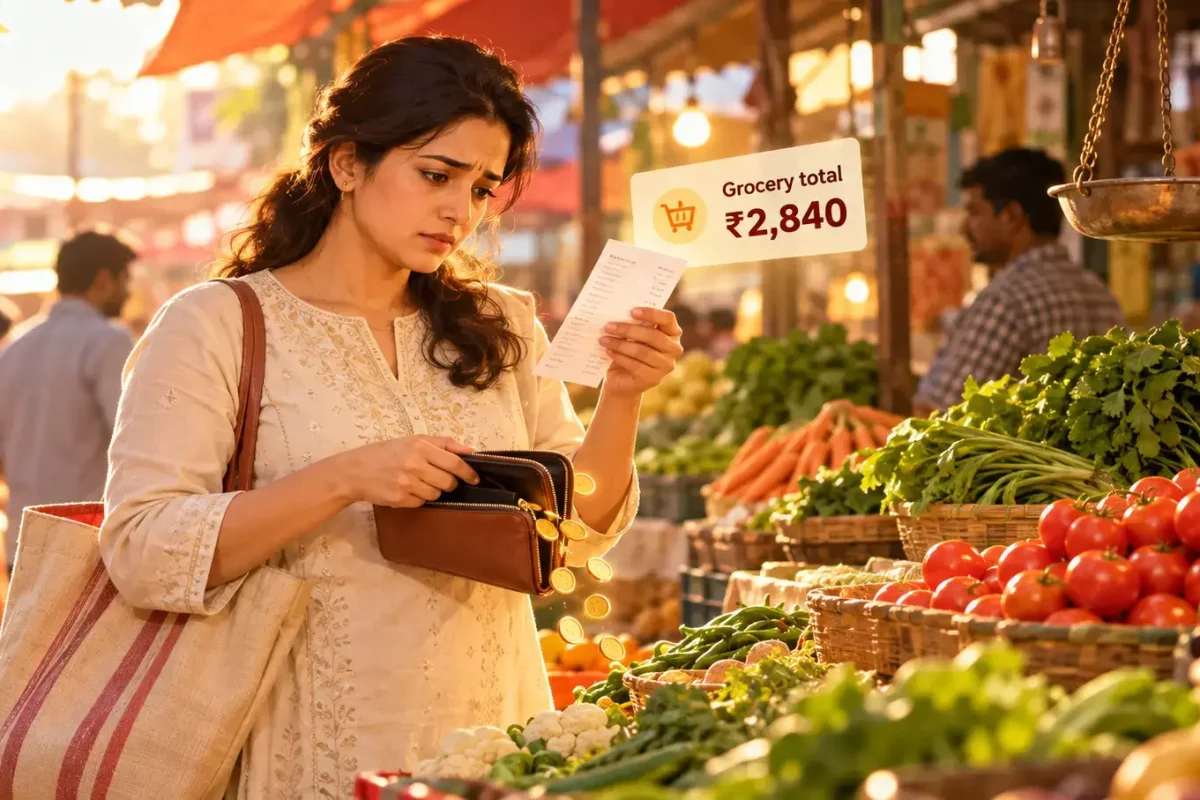
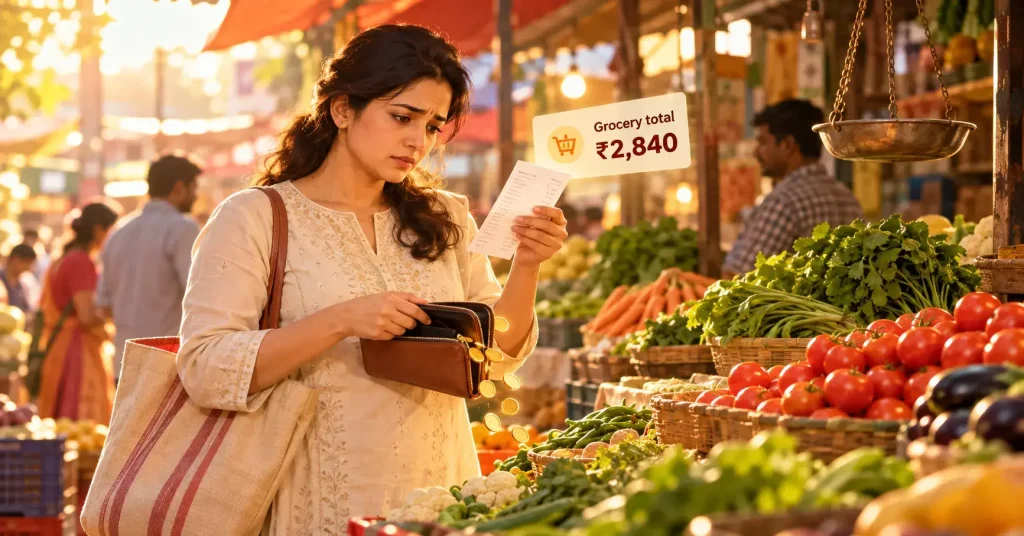
Your grocery bill can rise for reasons that have nothing to do with your shopping habits. A weak monsoon, a heatwave or a jump in vegetable prices can squeeze the same salary that already has to cover rent, school fees and EMIs. That is where the El Nino impact on household budget in India becomes a practical question, not just a weather headline.
El Niño can affect rainfall and temperature patterns, but it does not automatically mean a failed monsoon, dearer food or a bigger electricity bill in every Indian city. The effects vary by region, season and government response. Treating the forecast as a certainty can create unnecessary panic; ignoring household exposure can leave you scrambling.
This guide breaks down the likely pressure points, shows how to test your own monthly numbers and explains what to check before changing savings or repayment plans.
Key Takeaways
- El Niño is a climate pattern that can influence rainfall and temperatures; its effect on any one Indian household is uncertain.
- Food costs may move unevenly. A rise in a few vegetables is not proof that every grocery category will become more expensive.
- Hotter weather can increase cooling costs, especially where air-conditioning or frequent power use is already part of the household routine.
- EMIs usually do not change just because weather conditions change, but income disruption or higher essential spending can make them harder to manage.
- A small monthly stress test is more useful than guessing a national inflation number for your own kitchen.
- Keep decisions about savings, borrowing and investments grounded in your cash flow and current official information—not a single forecast headline.
What El Niño can—and cannot—tell you about household costs
Rainfall risk is not a household bill forecast
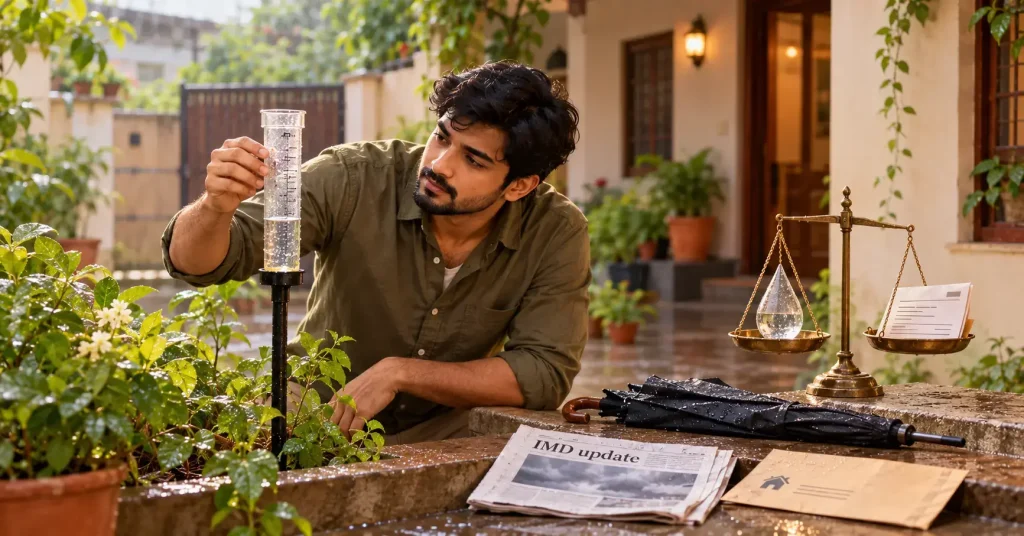
El Niño is a warming of surface waters in parts of the tropical Pacific that can influence weather patterns around the world. For India, it can be associated with a greater chance of below-normal monsoon rainfall, but the relationship is not a one-to-one prediction. The Indian Ocean, regional weather systems, timing and distribution of rain all matter. Check the India Meteorological Department (IMD) updates rather than treating a headline as a forecast for your district.
The El Nino impact on household budget in India is therefore best understood as a risk pathway: weather can affect crops, transport, power demand and some livelihoods; those changes may then affect household expenses or income. The path can be delayed, uneven and partly softened by supply decisions or public policy.
Separate exposure from speculation
Take Rukhsana, a nurse in Sopore with monthly take-home pay of ₹48,000. Her household spends around ₹10,000 on groceries, ₹3,000 on electricity and utilities, and ₹12,000 on loan EMIs. A weather-related increase in certain food items would matter, but so would an unexpected medical expense or a change in work shifts. The useful exercise is to identify which costs are exposed—not to assume every line will rise together.
For a household with fixed salary and a fixed-rate EMI, the first pressure may be everyday spending. For a farmer, a seasonal worker or a small food business, income could also be affected. The same climate event does not create the same budget problem for everyone. This is why the El Nino impact on household budget in India should be assessed against your own location, income sources and spending pattern.
Food prices: watch the basket, not one alarming item
Why the grocery bill can move unevenly
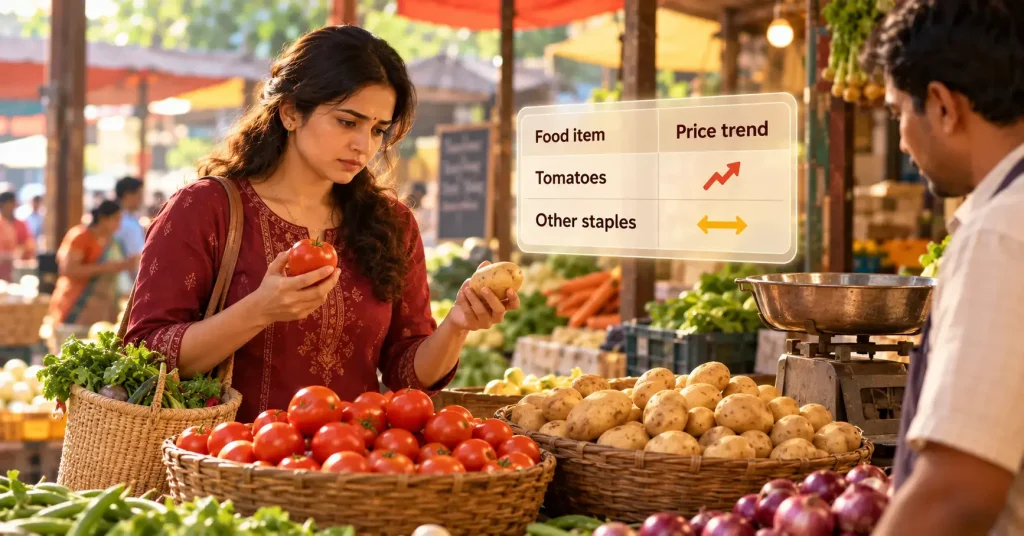
Rainfall shortfalls or intense rain can affect crops, harvest timing and transport. That may put pressure on selected foods, while other items remain stable or follow different seasonal patterns. The price you pay also depends on local supply, storage, distribution and the market you shop in. A sharp rise in tomatoes does not mean your full monthly food basket has risen by the same percentage. For broader context on price and inflation conditions, the Reserve Bank of India (RBI) publishes monetary policy and inflation-related information, though national measures cannot predict the cost of an individual household’s basket.
To understand the El Nino impact on household budget in India at home, compare actual spending across a few weeks. Keep the same categories—grains, vegetables, milk, cooking oil and other essentials—and note quantities as well as totals. Otherwise, a month with guests or a bulk purchase can look like inflation when it is simply a different shopping pattern.
Try it yourself: run a grocery stress test
Selvam, a bus depot clerk in Tirunelveli, budgets ₹9,000 a month for groceries. He lists his regular items and tests what happens if his essentials total ₹9,500 or ₹10,000 for one month. That extra ₹500–₹1,000 is a planning range, not a prediction that prices will rise by that amount. He can then see whether the difference would come from a flexible expense, an existing cash buffer or a temporary change in the monthly plan.
Use a simple table like this with your own figures. Do not cut nutrition or essential medicines to make the numbers look tidy; the point is to see the size of the gap.
| Monthly item | Usual amount | Stress-test amount | Difference |
|---|---|---|---|
| Groceries | ₹9,000 | ₹10,000 | ₹1,000 |
| Electricity and utilities | ₹2,500 | ₹3,200 | ₹700 |
| Transport | ₹3,000 | ₹3,300 | ₹300 |
| Total tested increase | ₹14,500 | ₹16,500 | ₹2,000 |
This example is a scenario, not a forecast for prices. Check current local prices and your own bills; the national picture may not match the market near your home. A household stress test is a practical way to explore the El Nino impact on household budget in India without treating an uncertain outcome as inevitable.
Electricity and cooling: heat shows up on the bill
More cooling can mean more units consumed
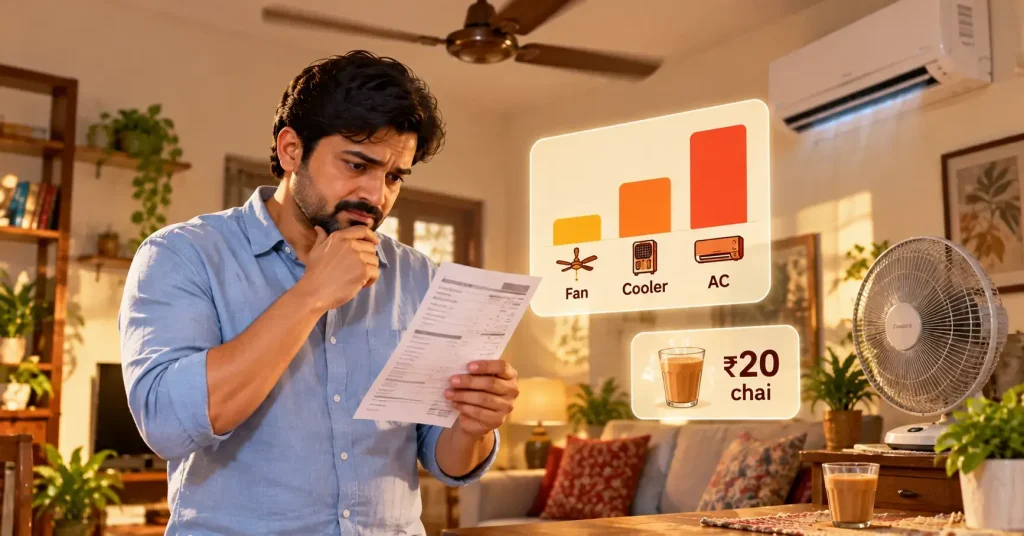
El Niño is not the only driver of a hot spell, and the link between a climate pattern and your next electricity bill is not direct. But hotter conditions can increase the use of fans, coolers and air-conditioners. The bill then depends on appliance efficiency, hours of use, household size, local tariff structure and whether your area has time-of-day or slab-based charges.
A ₹20 chai feels small; several extra hours of cooling every day can be a much larger recurring expense. If the bill rises, compare the units consumed with the previous month, not only the rupee total. A tariff change or a longer billing period can also alter the amount. This helps distinguish weather-related usage from other parts of the El Nino impact on household budget in India.
Make the comparison useful
Jamna, an accounts assistant in Ulhasnagar, usually pays about ₹2,800 for electricity. During a hot month, she tests a ₹3,500 bill against her current budget and checks the meter units when the bill arrives. The ₹700 difference is a planning stress test—not a claim about what her next bill will be. If the actual increase is smaller, the unspent amount remains in her household plan rather than becoming a reason to spend more elsewhere.
Look at your last three bills, note the units used and check the tariff details from your electricity provider. Practical changes such as using a fan where it is comfortable, setting cooling equipment sensibly and maintaining filters can help manage consumption, but they cannot eliminate heat or guarantee a lower bill.
EMIs, income and savings: where the strain can become serious
Weather does not automatically change a loan contract
Your home, car or personal-loan EMI does not rise simply because the monsoon is weak. The loan’s rate type, lender terms and any rate reset matter. The bigger household risk is indirect: when food, electricity or transport costs rise, less cash remains after essentials and fixed commitments. If seasonal income also falls, that gap can become harder to absorb.
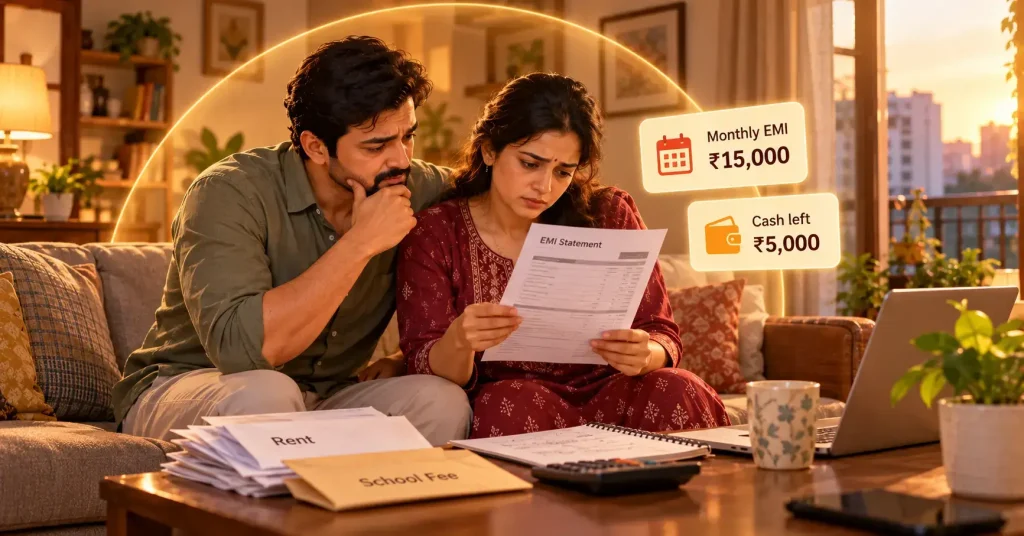
For example, a household with ₹15,000 in monthly EMIs and ₹5,000 left after essential expenses has little room for a sustained cost increase. A ₹2,000 monthly squeeze is not just an inconvenience if it pushes the family toward paying a credit-card bill late or taking expensive short-term borrowing. The El Nino impact on household budget in India may therefore show up as a cash-flow problem even when the EMI amount itself is unchanged.
Protect the monthly picture before making a big move
List take-home income, essential bills, debt payments and flexible spending separately. Test one difficult month and then two or three, because a short disruption and a prolonged income loss are different problems. If repayments become difficult, contact the lender through its official channel early and ask what options and costs apply. Do not assume a payment pause, loan restructuring or new borrowing will be available or suitable.
Keep savings accessible according to their purpose and terms. Withdrawing long-term savings or stopping a financial commitment can have costs, tax implications or other consequences. Review the relevant product documents and current rules before acting. For broader cash-flow basics, the Budgeting and Money Management hub and How to Budget on a Rs. 30,000 Monthly Salary in India offer related reading available on InvestingLens.
El Nino impact on household budget in India: build a weather-aware budget without guessing the future
Use a short, practical review
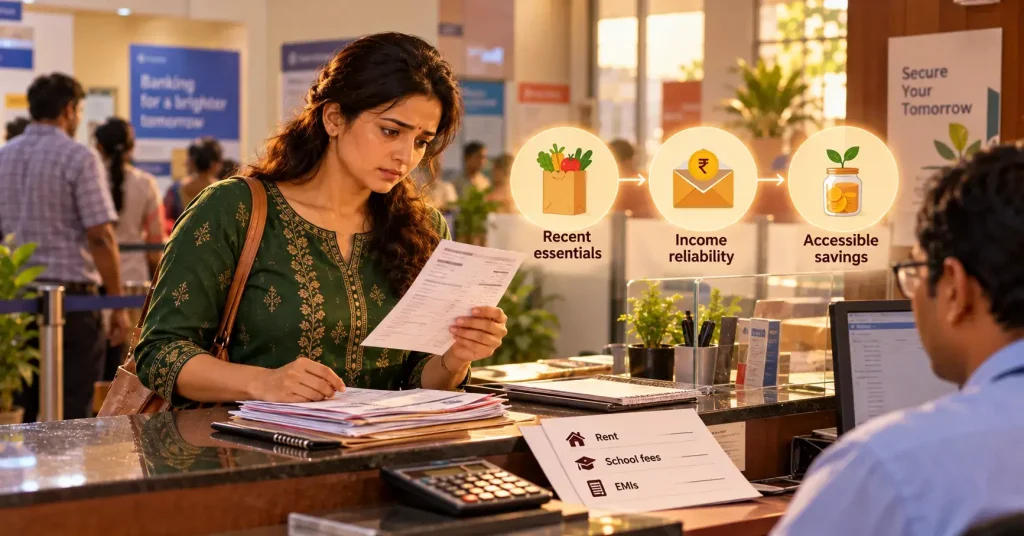
A budget does not need a climate model. It needs an honest view of what you spend and how much room you have. The El Nino impact on household budget in India can be tested using three inputs: your recent essential spending, your current income reliability and the amount of accessible savings available for an unexpected bill.
- Compare recent grocery and electricity bills with the same period in previous months, where possible.
- Write down fixed commitments such as rent, school fees and EMIs separately from flexible spending.
- Test a modest cost increase using your own figures; do not copy a percentage from a headline without checking what it applies to.
- Identify which expenses cannot safely be postponed and which are genuinely flexible.
- Check official weather and inflation updates periodically, rather than refreshing alarming predictions every day.
The article Budgeting and Money Management Skills: 5 Proven Steps to Master Your Cash Flow can help with the mechanics of tracking income and expenses. This is not about squeezing every small pleasure out of the month. A ₹20 chai is not the reason a household budget breaks; untracked recurring costs and no plan for a difficult bill are more revealing.
Know when a household budget needs a wider review
If a cost increase is temporary, the response may look different from a situation where income has fallen for several months. Check whether the strain is coming from prices, higher usage, lost workdays or an existing debt burden. Those causes need different answers. If a repayment problem is developing, a qualified credit counsellor or the lender’s official support channel may help explain available procedures and their consequences.
For a broader budgeting framework, Budgeting and Money Management Skills: 5 Proven Steps to Master Your Cash Flow is a relevant InvestingLens article. No single household plan can predict every weather-related disruption. It can, however, show where the first ₹500 or ₹2,000 of pressure would land, making the El Nino impact on household budget in India easier to discuss in concrete terms.
FAQs
Does El Niño always cause a bad monsoon in India?
No. El Niño can influence the probability of rainfall patterns, but it does not determine the monsoon outcome by itself. Check current IMD forecasts and updates for the relevant season and region.
Will El Niño make my grocery bill go up?
It may contribute to pressure on some food supplies, but the effect varies by item, location and season. Track your actual quantities and spending instead of assuming every grocery price will rise together.
Can El Niño increase my electricity bill?
Hotter weather can lead to more cooling use and higher electricity consumption, but the bill also depends on tariffs, appliance efficiency and billing periods. Compare units used as well as the amount charged.
Can a weather event change my EMI?
Weather alone does not change your loan agreement or EMI. Rate resets and lender terms govern the payment, while higher household costs or disrupted income can make an unchanged EMI harder to manage.
Final Thoughts
El Niño belongs in a household risk conversation, not in the role of a guaranteed price forecast. Food, cooling, income and loan payments connect through cash flow, but the pressure differs from one family and region to another. A local bill and a clear monthly budget are more useful than a dramatic headline.
Start by comparing your latest grocery and electricity figures with your usual month, then run a one-month stress test against take-home income and fixed commitments. For weather context, check the latest IMD information; for personal debt or savings decisions, review official product terms or speak with a qualified professional. The worked examples in this article are illustrations, not forecasts or personal financial advice.
The examples above are simplified, and their figures are assumptions used to show how the numbers work.
This article is for educational purposes only and does not constitute financial advice. Figures, examples, and outcomes are illustrative and vary based on individual circumstances and lender policies. Always consult a certified financial advisor before making major financial decisions.
One Email a Week. Five Things Worth Knowing.
- One important financial change that actually affects you
- One practical money lesson
- One useful calculator
- One common mistake to avoid
- One guide worth reading