Digital Loan App Contact List Harassment India: 7 Proven Steps to Protect Your Circle
A lender or recovery agent calling your contacts about your loan can feel like the whole neighbourhood has been handed your private business. The pressure is real; so is the need to respond carefully. Sending an angry message or paying an unknown UPI ID may make things worse.
Digital loan app contact list harassment India is not something you have to treat as a normal collection tactic. Keep the loan question and the privacy question separate: verify what you owe through the lender, and document any unauthorised exposure of your contacts. Understanding digital loan app contact list harassment India starts with treating the reported conduct and the loan balance as separate matters.
This guide explains what to record, how to limit further access, where to raise a complaint and what not to do while you work out the next step.
Key Takeaways
- Save call logs, messages, screenshots and the app’s name before deleting anything.
- Ask the people contacted to preserve evidence and avoid arguing with callers.
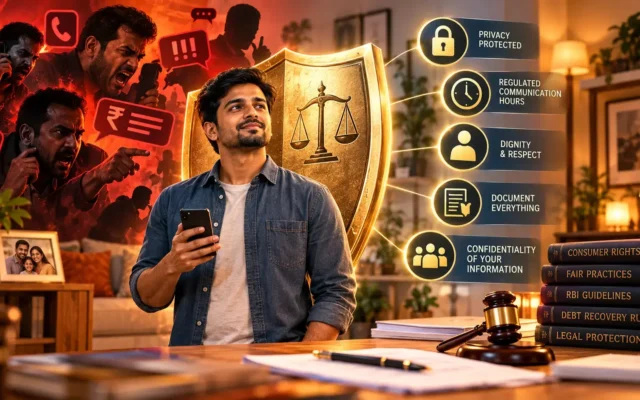
- Review app permissions and revoke access that is not needed; uninstalling alone may not remove data already collected.
- Verify the lender and outstanding amount directly through an official channel before paying.
- Complain to the lender first, then consider escalation to the relevant regulator or official cybercrime reporting channel, depending on the issue.
- Do not share OTPs, passwords, screen access or payment details with callers claiming they can stop harassment.
Digital loan app contact list harassment India: what contact-list misuse can look like
Pressure delivered through people you know
Contact-list misuse may involve calls or messages to relatives, colleagues, references or other people whose numbers were stored on your phone. A caller might disclose that you borrowed money, make threats, send embarrassing messages or urge your contacts to pressure you. A contact being called is not, by itself, proof of who accessed the number or whether the lender authorised the contact.
Digital loan app contact list harassment India becomes especially distressing when the message is designed to shame rather than resolve an account. Keep the language factual in your records: note what was said, who received it, the date and the number or account used. When documenting digital loan app contact list harassment India, record the specific disclosure rather than making assumptions about how the information was obtained.
Permissions are not the same as unlimited consent
An app may request access to phone features during installation or use. A permission screen does not tell you, on its own, how a particular lender handles information, whether it has been shared, or whether a recovery caller is authorised. Read the app’s privacy information and check the lender’s identity independently. This distinction is important when assessing digital loan app contact list harassment India, because permission to access a device feature does not by itself explain or justify every later use of information.
Changing a permission can help limit future access from your device, but it cannot retrieve information that may already have been copied or shared. That is why preserving evidence matters as much as tightening settings.
Take Jagat’s situation
Jagat, a 34-year-old nurse in Nainital, has a monthly take-home income of ₹42,000 and is trying to manage a ₹18,000 app-loan balance. His sister receives a message naming the loan and urging her to make him pay. Jagat has two separate jobs now: confirm the balance with the lender using an official contact route, and save his sister’s message as evidence of the disclosure. Paying the caller who sent the message would not answer either question. His response shows how someone facing digital loan app contact list harassment India can protect a record while still verifying the loan.
What to do in the first 24 hours
Build a clean evidence file
Save screenshots showing the full message, sender details, date and time. Export or photograph call logs, keep voicemail and note the names of contacts who were approached. Ask them to forward the original message where possible rather than paraphrasing it. Store copies somewhere you can access if your phone is lost or the app is removed.
Do not edit screenshots to add commentary. Make a separate timeline: when the app was installed, when the loan was taken, when contact-list access was requested, and when third parties were contacted. Include the app name, any lender named in the agreement, loan account details and the caller’s number. Avoid posting personal information publicly. A clear timeline can make a digital loan app contact list harassment India complaint easier to explain to the lender or an authority.
Secure your phone without destroying evidence
Review permissions in your phone settings. Revoke contact access if it is not needed, and check other permissions that seem unrelated to the service. Keep the app and messages long enough to record relevant details; then consider whether removing the app is appropriate. An uninstall does not prove that stored data has been deleted.
Change passwords if you suspect account access, enable device security features and never read an OTP to a caller. Do not install remote-access software because a caller says it is needed to resolve the complaint. These precautions can reduce additional risks while you address digital loan app contact list harassment India through documented channels.
Tell your contacts what to do
Vimala, a 39-year-old school administrator in Udupi, has a ₹25,000 monthly household budget to manage and learns that a colleague received a collection message. She can ask the colleague to save the message, block the sender if needed and avoid sharing her workplace details or forwarding the message to a wider group. A brief, calm explanation can reduce panic without exposing additional financial information.
Your contacts do not need to negotiate your loan, send money or disclose their own personal details. If someone threatens them, they should document the threat and use the appropriate complaint channel themselves. For digital loan app contact list harassment India, their original messages or call records may also help establish what happened.
How to complain without losing track of the loan
Contact the lender through a verified route
Find the lender’s name in the loan agreement, sanction communication or official app listing, then locate its customer-care or grievance channel independently. Describe the specific conduct, attach copies of evidence and ask for a complaint reference number. Request that the lender investigate who contacted your contacts, what information was disclosed and what steps it will take to stop further unwanted contact.
Keep your repayment discussion separate. Ask for a written account statement and a clear breakdown of the amount claimed, including any charges. Do not rely on a recovery caller’s personal UPI ID or a payment link sent in a threatening message. Confirm payment instructions through an official lender channel.
Escalate through the right channel
If the lender does not resolve a complaint, check the lender’s official grievance process and the current RBI complaint mechanism to see whether the entity and issue fall within its scope. For suspected online misuse, impersonation, threats or financial cybercrime, use official cybercrime reporting channels and preserve the complaint acknowledgement. For an immediate threat to physical safety, contact local police or emergency services.
Digital loan app contact list harassment India can involve more than one issue: recovery conduct, privacy, impersonation or a suspected scam. Describe the facts rather than guessing which law was broken. A regulator or police authority can assess the appropriate route. If you report digital loan app contact list harassment India, include the complaint reference and relevant evidence when following up.
Keep a paper trail and a realistic timeline
Zoliana, a 31-year-old electrician in Lunglei, earns about ₹36,000 a month and receives a call saying his contacts will be messaged unless he pays that day. He records the call time, saves the number, contacts the lender through its published channel and submits a written complaint. He does not assume that a complaint instantly cancels a genuine loan balance; he asks for confirmation of the account and keeps copies of each response.
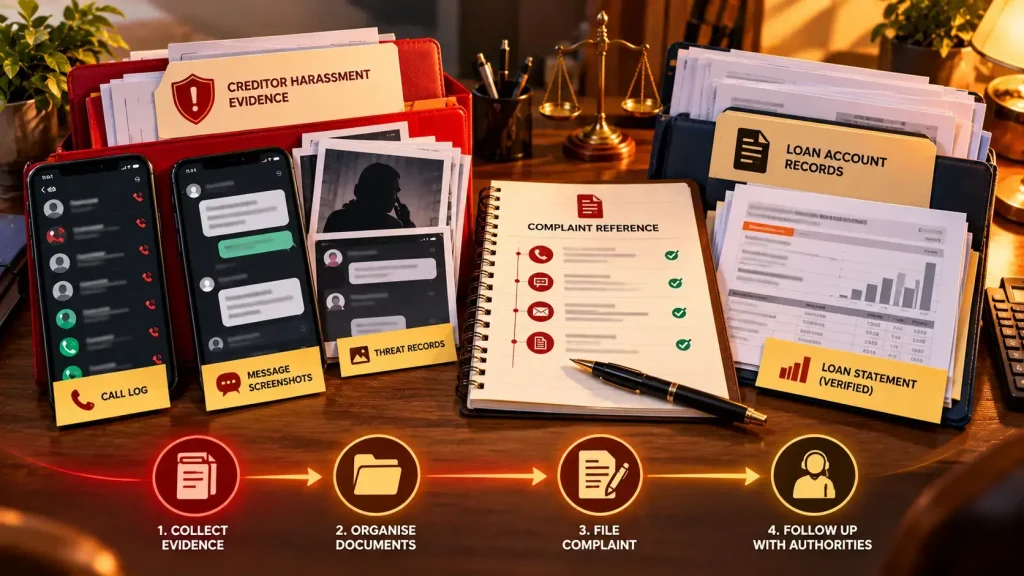
Use a simple tracker so the pressure does not scatter your records:
| Record | What to keep | Why it helps |
|---|---|---|
| Calls and messages | Date, time, number, screenshots, exact words | Shows the pattern and specific conduct |
| People contacted | Who received contact and a copy of the original message | Documents contact-list impact without relying on memory |
| Lender complaint | Submission copy, attachments and reference number | Proves when and how you raised the issue |
| Loan account | Agreement, statement and verified payment receipts | Keeps the debt balance distinct from the harassment complaint |
Common mistakes that can deepen the problem
Paying a caller just to make the messages stop
A payment to an unverified account may not reduce the loan balance. Check the beneficiary and payment route with the lender first, and retain the receipt. If you have already paid a suspicious account, preserve the transaction details and report it promptly through official channels.
Deleting everything in anger
Removing the app or blocking every number may feel like relief, but it can also erase information you need to identify the lender or establish a timeline. Save the evidence first. Blocking a number after recording its details may still be sensible if calls are distressing.
Ignoring the account because the recovery conduct is wrong
Harassment and repayment are separate issues. A threatening call does not establish the correct loan balance, and a complaint does not automatically settle or cancel the debt. Request an account statement and raise any dispute in writing. If repayment is becoming unmanageable, explore legitimate support rather than taking another high-cost loan under pressure.
For context on abusive collection behaviour, see The Phone That Would Not Stop Ringing: 7 Warning Signs of Debt Recovery Harassment in India. If the app or caller offers to erase the balance for an upfront fee, treat that as a separate warning sign and verify everything independently.
FAQs
Can a loan app contact my friends and family in India?
Whether a particular contact is permitted depends on the facts, the lender’s practices and applicable rules; do not assume that app permission means unlimited disclosure. Save evidence of what was shared and raise a written complaint with the verified lender.
What should I do if a loan app threatens to message my contacts?
Record the threat, secure your account and contact the lender through an independently verified channel. Do not pay a personal account or share OTPs to make the threat disappear.
Will uninstalling a loan app delete my contact data?
Not necessarily. Uninstalling can remove the app from your phone, but it does not establish that information already collected or shared has been erased.
Where can I report digital loan app harassment in India?
Start with the lender’s grievance channel and check the current RBI complaint process for eligibility. For suspected cybercrime, impersonation or threats, use official cybercrime reporting channels; contact local police for immediate safety concerns.
Final Thoughts
Contact-list misuse works by making you feel exposed and rushed. Slow the situation down: preserve the record, verify who is actually collecting the loan and keep every complaint and payment traceable. That does not make the stress disappear, but it gives you a clearer basis for responding.
Check the lender’s official grievance details and the current RBI or cybercrime reporting guidance relevant to your case. If the loan balance itself is disputed or repayment has become difficult, a qualified legal or financial professional can help you understand your options without confusing them with the conduct complaint.
The examples above are simplified, and their figures are assumptions used to show how the numbers work.
This article is for educational purposes only and does not constitute financial advice. Figures, examples, and outcomes are illustrative and vary based on individual circumstances and lender policies. Always consult a certified financial advisor before making major financial decisions.
One Email a Week. Five Things Worth Knowing.
- One important financial change that actually affects you
- One practical money lesson
- One useful calculator
- One common mistake to avoid
- One guide worth reading