
Debt Relief in India: Real Options, Costs and Scams to Avoid (2026)
If EMIs and credit card dues are growing faster than you can pay them, you will see ads for “debt relief companies” promising to cut what you owe. The truth is less exciting: in India there is no regulated, government-approved category called a debt relief company, so no list can honestly name a “best” one. What does exist is a set of real options, most of them free or low cost, that you should try first. This guide explains each one, what it costs, what it does to your CIBIL score, and how to judge any company that asks for money.
Update note: an earlier version of this page listed debt settlement firms that mainly operate in the United States. We removed them because they are not relevant to Indian borrowers. This page is educational, not legal or financial advice.
Quick answer: are debt relief companies worth it in India?
Usually not as a first step. Most of what a paid company does, such as negotiating with your lender, you can do yourself or with a free counsellor. A company may make sense only after you have tried the options below, if the fees are small and written down, and if nothing is collected before it delivers a result. Never stop paying EMIs on the advice of a company without understanding the damage to your credit score.
Your real options, in the order to try them
1. Talk to your lender first (restructuring or lower EMI)
Call or write to the bank or NBFC before you miss a payment. Ask about extending the loan tenure to lower the EMI, a short repayment holiday, or converting a credit card balance into a fixed EMI plan. Lenders prefer a smaller regular payment to a default. Send the request in writing or by email so you have a record, and note the name of the person you spoke to.
2. Free credit counselling
In 2009 the RBI issued a model scheme for Financial Literacy and Credit Counselling Centres, whose aims include free debt counselling and helping borrowers in distress prepare restructuring plans (see the RBI circular). One well-known example is Disha, started at the RBI’s instance and run with ICICI Bank’s CSR support, offering free counselling to people regardless of which bank they use. Centres and locations change over time, so check the current status with your bank or the RBI before relying on a specific centre. Our guide on how credit counselling works in India explains what to expect.
3. Consolidate or move your debt to a cheaper one
A personal loan or balance transfer at a lower interest rate can replace several expensive debts, especially credit card balances, which often cost far more than a personal loan. This only helps if you stop adding new debt and the new EMI is truly lower. See our guides to debt consolidation loans in India and balance transfer cards.
4. Compromise settlement with the lender
If you genuinely cannot repay in full, lenders can agree a one-time settlement, paying less than the full amount to close the loan. In June 2023 the RBI issued a framework covering compromise settlements and technical write-offs for banks, NBFCs and other regulated lenders (see the RBI circular). Settlement is a legitimate route, but it has a cost:
- Your account is usually reported to credit bureaus as “settled” and not “closed”, which lowers your CIBIL score and stays visible for years.
- Lenders may refuse new loans or offer worse rates for a long time afterwards.
- You must get the settlement terms in writing before paying, and a no-dues or closure letter after paying. Never pay a settlement amount to a personal account.
Read our comparison of debt settlement vs debt consolidation and our guide to negotiating credit card debt before deciding.
5. Legal and formal routes
- Lok Adalat or pre-litigation settlement. Many lenders settle recovery disputes through Lok Adalats, which are free to use. Ask your lender or the District Legal Services Authority.
- Consumer and banking complaints. If the lender acted unfairly, you can escalate a complaint (see the complaints section below).
- Insolvency. Formal personal insolvency under the IBC is not a practical option for most ordinary borrowers. Speak to a lawyer if you face court action.
6. Paid debt management or “debt relief” companies
This is the least regulated option. To our knowledge, the RBI does not approve or license private debt settlement agencies as a category, so anyone can use the name. If you are still considering one, use the checklist below and read our guide to the signs a debt relief offer is a scam.
Comparison of your options
| Option | Best for | Typical cost | Effect on credit score |
|---|---|---|---|
| Restructure with lender | You are still paying but struggling | Usually none, sometimes a processing fee | Neutral if agreed before missing payments |
| Free credit counselling | You need a plan and a negotiator | Free | None directly |
| Consolidation or balance transfer | Several high-interest debts, steady income | Processing fees and new interest | Can improve it if you pay on time |
| Compromise settlement | You cannot repay in full | You pay a reduced lump sum | Marked “settled”, lowers score |
| Lok Adalat | Disputes already in recovery | Free | Depends on the agreed outcome |
| Paid debt relief company | Rarely the best choice | Fees, often a percentage of debt | Often hurts, especially if you stop paying |
Checklist before paying any debt relief company
- Ask for a written agreement that lists every fee, in rupees, before you pay anything.
- Do not pay large upfront fees. Be cautious about any company that charges before it has negotiated anything.
- Never agree to stop paying EMIs without understanding the effect on your CIBIL score and the legal notices that can follow.
- Pay settlement money only to the lender’s own account, never to the company’s personal account.
- Ask for the lender’s settlement letter in writing, and confirm directly with the lender.
- Search the company name with “complaint” or “fraud”, and be wary of guaranteed results such as “loan waiver” or “instant CIBIL repair”.
- Do not share OTPs, net banking details or originals of documents.
Your rights when lenders or recovery agents pressure you
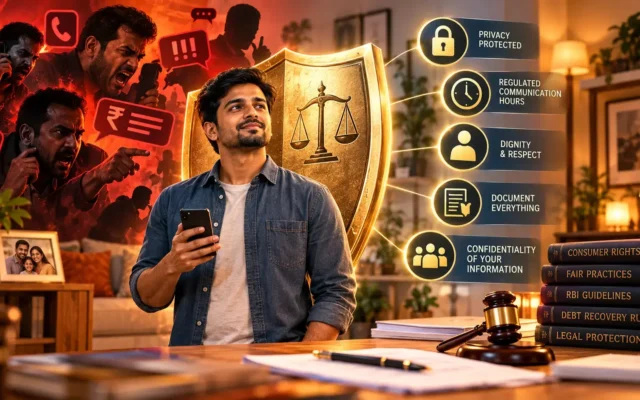
Since August 2022, RBI instructions bar recovery agents of banks and NBFCs from intimidation or harassment and from calling borrowers before 8 am or after 7 pm (see this Business Standard report). Agents are expected to carry identification and authorisation from the lender and to use only the contact details the lender has on record. In February 2026 the RBI also issued draft rules to tighten recovery conduct further, so check the RBI website for the final version and its effective date. Read more in our guides on recovery harassment and your rights under the Consumer Protection Act.
How to complain
- Write to the lender’s grievance officer and keep the complaint number.
- If you receive no reply within 30 days, or the reply does not satisfy you, file a complaint under the RBI Integrated Ombudsman Scheme at cms.rbi.org.in or call the toll-free number 14448. Check that your lender is covered by the scheme.
- For threats or abuse, you can also report to the police.
A simple plan to follow
- List every debt with the amount, interest rate and EMI.
- Contact your lender first and ask for restructuring in writing.
- Try free credit counselling for a repayment plan.
- If your income can support it, consolidate expensive debt and use a payoff method such as snowball or avalanche.
- Consider settlement only if you truly cannot repay, and get everything in writing.
- Check your report afterwards and learn how your CIBIL score works so you can rebuild.
Frequently asked questions
Are debt relief companies legal in India?
Private companies can offer debt advice and negotiation services, but to our knowledge there is no RBI licence specific to them. Their legality depends on how they operate, and what they promise matters. Guaranteeing a loan waiver or asking you to stop paying EMIs are warning signs.
Will debt settlement hurt my CIBIL score?
Yes, usually. A “settled” status signals that you paid less than the full amount, which lowers your score and can affect future borrowing for years.
Can a lender harass me for repayment?
No. RBI instructions prohibit intimidation and harassment by recovery agents, and calls are barred before 8 am and after 7 pm. Keep records and complain to the lender and, if unresolved, through the RBI complaint system.
What is the safest first step if I cannot pay my EMIs?
Contact your lender before you miss payments, ask for restructuring in writing, and speak to a free credit counsellor. These steps cost nothing and keep your credit options open.
This article is for educational purposes only and does not constitute financial advice. Figures, examples, and outcomes are illustrative and vary based on individual circumstances and lender policies. Always consult a certified financial advisor before making major financial decisions.
One Email a Week. Five Things Worth Knowing.
- One important financial change that actually affects you
- One practical money lesson
- One useful calculator
- One common mistake to avoid
- One guide worth reading